Monday 12th October 2026
Next-generation infrastructure: growth without giving up the downside
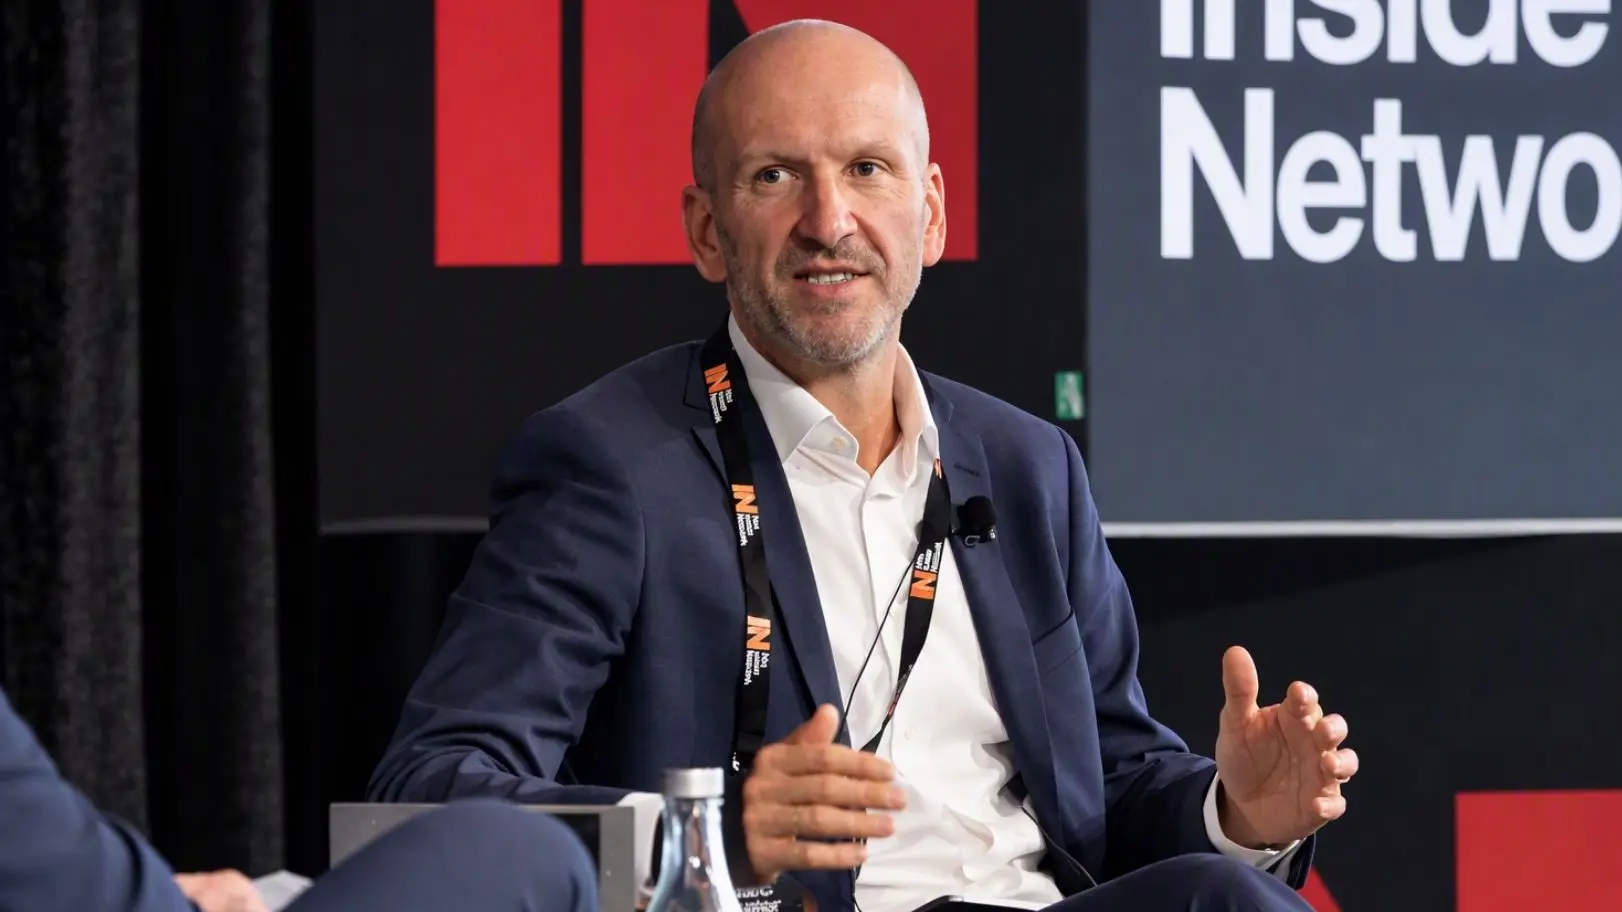
Partners Group's Marc Meier says next-generation infrastructure keeps the asset class's downside protection while adding real growth, and that secondaries are at an inflection point, so long as advisers look inside concentrated portfolios and remember semi-liquid is not liquid.
For most of the last two decades, infrastructure meant regulated monopolies: utilities, airports, toll roads, each tied to government as regulator, price-setter or counterparty.
Marc Meier, managing director for private infrastructure partnerships investments at Partners Group, says a different category has grown up alongside them, and it changes what the asset class can do in a portfolio.
The new assets sit on top of what Meier calls gigatrends. These are the long-running shifts reshaping economies over the next fifteen to twenty-five years: digitisation, demographic change and the energy transition.
They still carry the classic infrastructure traits an adviser values: downside protection, insensitivity to the economic cycle and inflation linkage. But because they sit in a growing segment, they add something regulated assets cannot.
“These next-generation assets keep a lot of the upside without giving up the downside protection,” Meier says. Traditional infrastructure caps the upside through regulation; the newer assets keep it.
The next generation
The catch is that a powerful trend does not automatically make a good investment. Meier is blunt that the hottest corner is also the riskiest. Data centres are the obvious example.
Demand is surging, but no one knows whether a given asset grows at 15, 20 or 25 per cent a year. That difference compounds into a very different place by 2030.
“We think data centre valuations in the US, and probably parts of Europe, are pretty expensive, and when valuations correct you can run into problems with the downside protection part of your investment case,” he says.
That is crucial, if investors pay too much for the growth story and the very feature that justified the allocation, the protection on the downside, is the first thing to go.
Partners Group’s response is to go a level below the trend. In data centres it favours the Asia-Pacific region, which has around 60 per cent of the world’s population but only about 30 per cent of its data centre infrastructure, on the view that the fundamentals are better priced than in the crowded US market.
Secondaries inflection point
The bigger opportunity, on Meier’s reading, is in how the exposure is bought. Infrastructure secondaries involve an investor buying an existing fund position from another who wants liquidity. They are, he says, at an inflection point.
Transaction volumes have grown 30 to 35 per cent a year since the early 2020s, reaching around US$20 billion in 2025. He expects them to at least double by the end of the decade.
Private infrastructure assets under management will help drive that growth, growing perhaps 70 to 80 per cent over five years. The fact that infrastructure secondaries sit fifteen to twenty years behind the more mature private equity secondaries market will help too.
Meier’s firm says it did the industry’s first infrastructure secondary in 2006. He argues the discount is only one piece of the puzzle. On Partners Group’s own record, the discount accounts for only about 13 to 14 per cent of the total return. More than 85 per cent is created once the asset is in the portfolio.
That matters more in infrastructure than in private equity because of concentration. A private equity secondary might hold a diversified portfolio of 30 to 50 companies.
In infrastructure, “most portfolios are single-fund secondaries, or small portfolios,” Meier says. So a single underlying asset carries real weight. Buying the discount without understanding what sits inside is where the risk lives.
Building the allocation
For advisers constructing an allocation, Meier makes two practical calls. The first is size: he prefers mid-cap over large-cap infrastructure, because large-cap investment cases increasingly assume an IPO exit, and building a thesis on a single exit route is fragile. He says mid-cap also brings simpler value-creation stories and less execution risk.
“Mid-cap gives you more optionality and less exit risk.”
The second is to hold both direct and secondary exposure rather than choosing. The two move differently: direct investing does best in bull markets, while secondaries came into their own through the rate rises and turmoil of 2022 to 2024, when direct dealmaking slowed. “Having both gives you a natural hedge,” Meier says, and an instrument suited to whichever conditions arrive.
He is equally clear about what the newer semi-liquid and evergreen vehicles are not. They have cut minimum tickets to as little as $1,000 or $10,000 and pay some liquidity, but the underlying assets have not changed.
“Let’s not forget this is still an illiquid asset class,” he says. “Those instruments are called semi-liquid, they’re not something to trade in and out of.”
Three to five years is the minimum horizon. A vehicle blending direct and secondary holdings will generally meet redemptions in a stressed market better than a concentrated, direct-only one. That is because more of the portfolio is throwing off cash.
On Meier’s view, it fits in one of two places. It can replace part of the bond allocation, or serve as the most stable, least volatile portion of a private equity sleeve.
A value-add approach with some secondaries, he says, can deliver 10 to 15 per cent net “fairly comfortably.” The work for an adviser is to buy the growth without overpaying for the fashionable end of it, and to keep enough diversification that the illiquidity never becomes the whole story.
Laurence Parker-Brown is head of content at The Inside Network and managing editor of The Inside Adviser and Investor Strategy News.