

Thursday 29th October 2026
The defensive asset class that is trading at a discount
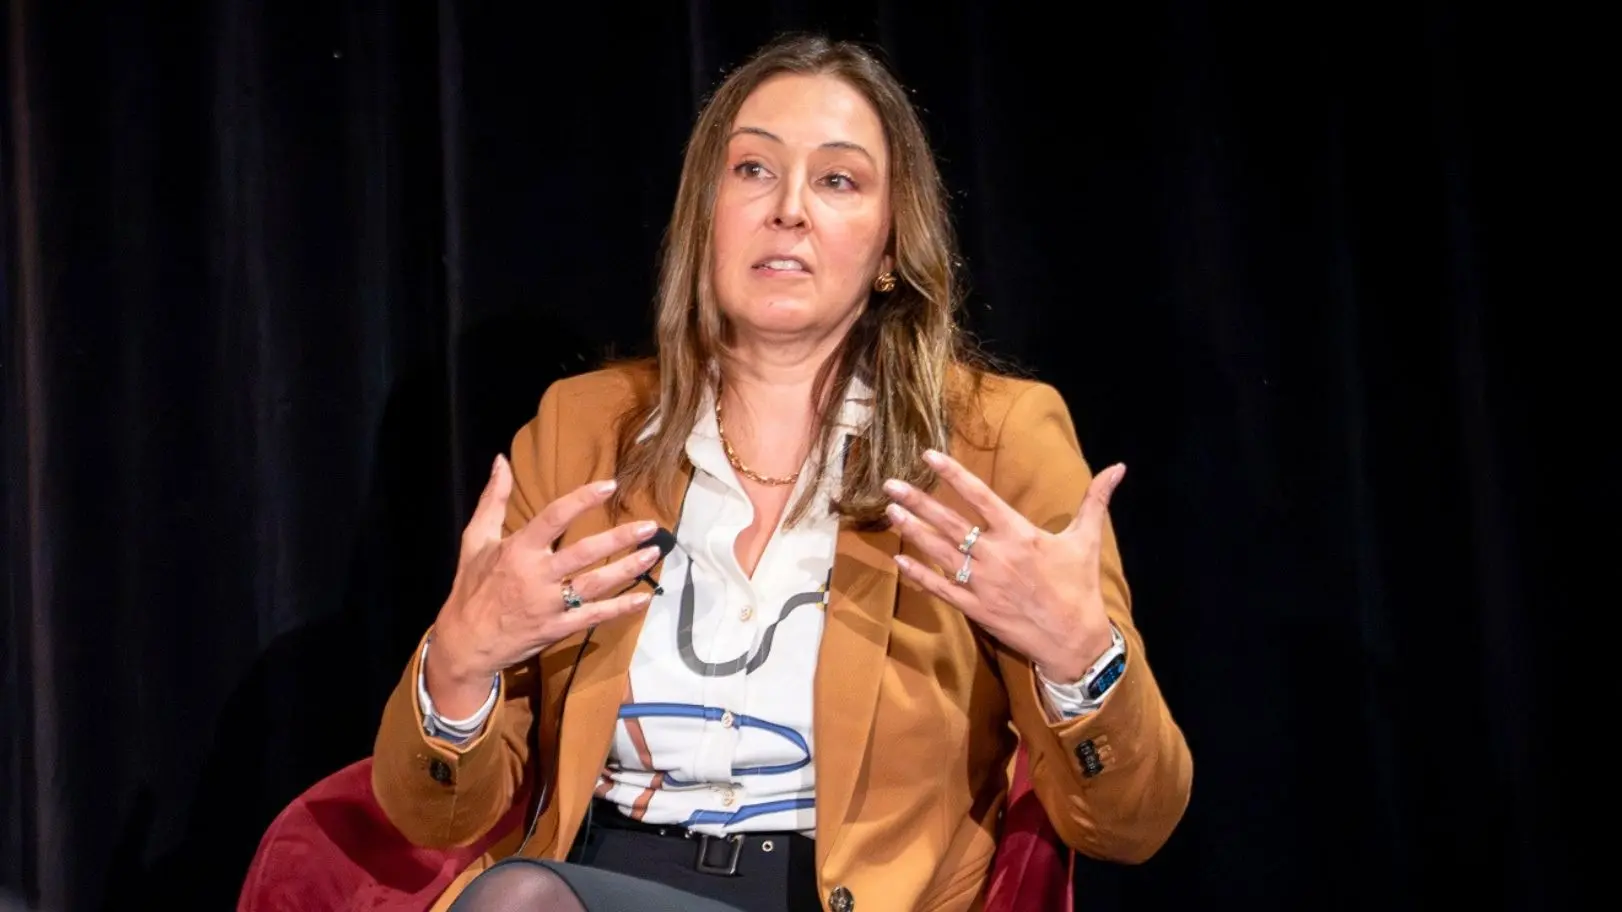
Cohen & Steers’ Michelle Butler says listed infrastructure has averaged a 7 per cent premium to global equities over 20 years and sits at a 15 per cent discount today. The discount has arrived alongside the strongest demand story the asset class has had in decades.
Investors primarily buy infrastructure for diversification, inflation beta, and what it does in a falling market, and they have historically paid for the privilege. Michelle Butler, senior vice president and portfolio specialist at Cohen & Steers, puts the trade in one line.
“Infrastructure assets are well placed for potential upside participation while offering downside resilience,” Butler says. The asset class tends to participate but lag a rising equity market and defend on the way down, which is why it has usually carried a valuation premium.
That premium has gone. Measured against the MSCI World, the FTSE Global Core Infrastructure 50/50 index has averaged a cash flow multiple premium (based on EV/EBITDA) of roughly 7 per cent over the past two decades and now sits at a discount of about 15 per cent.
The power call
The discount is unusual because it coincides with demand conditions the sector has not seen before. US utility load growth was close to flat for the better part of three decades and is now running at 3 to 5 per cent, with analysts still revising estimates upward.
Data centres account for the largest share, alongside reindustrialisation, electric vehicles and ordinary residential demand.
The scale is easier to grasp at company level. Butler points to Evergy, the Kansas and Missouri utility, which took 145 years from its 1880 foundation to build 11 gigawatts of generation and now faces demands for another 15 gigawatts in short order.
Entergy, which operates across Texas, Louisiana, Mississippi and Arkansas, is building new generation dedicated to Meta’s Louisiana data centre campus, on her account 10 plants, with Meta significantly financing the build rather than the utility carrying the cost base.
That structure answers the stranded asset question which usually follows a commitment of that size, and Butler is clear it is not the normal arrangement.
Globally, the infrastructure investment requirement runs to $106 trillion, against government balance sheets that cannot fund it all. Butler puts the resulting shortfall at about $27 trillion, filled through privatisations, redevelopment of legacy assets and new listings.
Dispersion
Infrastructure covers broad sectors such as, utilities, transportation, communications and midstream energy, with something like 13 or 14 subsectors beneath them.
The gap between the best and worst performing subsector has averaged around 30 per cent a year over the past five years. Within communications last year, the best performing stock rose 56 per cent and the worst fell 58 per cent.
“Three years ago, I would never say exciting and infrastructure in the same sentence, because it’s defensive equity. I’ve since changed my tune.”
That dispersion is the argument for holding infrastructure selectively via active management rather than through an index. Electric utilities behave one way through a recession, midstream another in a cyclical upswing, and towers are capital intensive enough to struggle when rates rise. Owning the sector as a block means owning all of those outcomes at once, diversifying the risks.
The discount
The valuation gap deserves a second look before anyone reads it as a signal. Investors measure it against global equities, and global equities have changed, with the MSCI World now carrying a far heavier weight in a handful of expensive technology names than it did across most of the period that produced the 7 per cent average premium. A discount to that comparator says something about both sides of the comparison.
Butler’s thesis is that the themes are enduring rather than tactical, running from power demand through the digitisation of assets to the rerouting of trade flows as supply chains are rebuilt. Each of those plays out over years rather than quarters, and each favours different parts of the universe at different points.
Laurence Parker-Brown is head of content at The Inside Network and managing editor of The Inside Adviser and Investor Strategy News.