Thursday 12th November 2026
Yield is easy to find, the risk behind it is the harder question
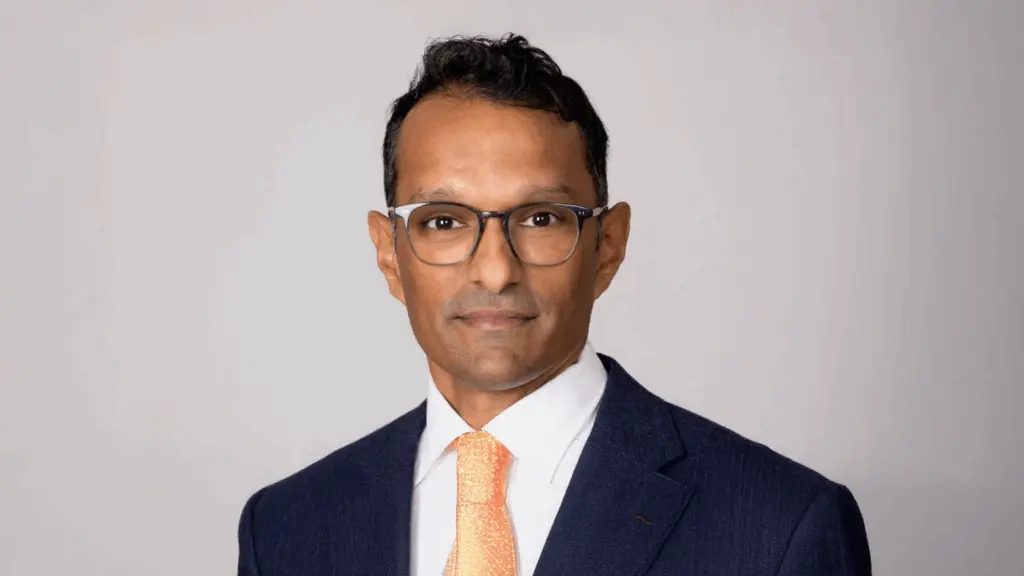
Yuan Tian, Executive Director, Multi-asset Indices at S&P Dow Jones Indices (S&P DJI) says income portfolios are usually assembled by stacking the highest yields on offer, when the more useful exercise is identifying which risk each stream is paying for. Most of those risks behave the same way in a crisis.
Income portfolios tend to get built one holding at a time, with the highest available yield winning each decision. Yuan Tian, Executive Director, Multi-asset Indices at S&P Dow Jones Indices, argues that the number on the page is the least interesting part of the exercise.
“If you’re trying to achieve 6 per cent yield, it’s not necessarily a 6 per cent income stream. Sometimes you’re simply receiving your own capital back,” Tian says.
The distinction between a distribution and a total return matters more once investors take inflation off the top, and it matters more again in Australia, where portfolios already concentrate in banks, resources, energy and the franking credits attached to them. Diversification in that context means diversifying the income engines rather than the ticker codes.
The ladder
Each source of income is payment for a specific risk. Cash carries reinvestment risk, since a deposit earning around 4 per cent today has to be reinvested at whatever the rate is on maturity.
Sovereign bonds add duration, the price of committing capital for longer, and, as the European sovereign debt crisis demonstrated, not every government bond is a safe haven. Corporate credit adds the possibility of default, and behaves differently depending on the weather.
“Credit often looks quite defensive when the market is quite calm. But when there is a crisis in the market, credit actually moves more like an equity security and less like a fixed income security.”
Dividend equities carry their own risk , since a yield rises when a price falls, and a company paying more to retain investors while its fundamentals deteriorate is not a higher quality holding. Real estate and infrastructure bring rates and financing risk, and both tend to trade like equities when markets are under stress.
Selling the upside
Providers usually present the option premium strategies that have drawn substantial flows across the United States and the Asia Pacific region as an income stream with low correlation to equity risk. Tian calls that the most misunderstood income in a portfolio.
“By selling calls in your underlying, you’re essentially exchanging the future upside for an income stream that you can monetise right now,” Tian says.
A covered call overlay monetises uncertainty. That means a volatile market pays a larger premium, and that premium can cushion a drawdown. It does not remove the drawdown. The underlying index, such as the S&P/ASX Buywrite Index, is still there beneath the overlay. It also requires a view.
A strategy that caps the upside is a reasonable holding in a range-bound market and an expensive one in a rising market. That makes it a market call rather than a diversifier.
Correlations
The common thread is that these risks are only distinct in ordinary conditions. Tian’s argument is that investors should examine correlation under stress rather than in calm. That is because investors flock to the same small set of safe haven assets whatever the cause of the crisis. As a result, the diversification benefit thins out at the moment it is needed.
Two consequences follow for portfolio construction. Risk limits become forced sellers. A portfolio breaching its volatility guardrail has to cut exposure at the worst possible point, regardless of whether anything in it is likely to default. And drawdown is not only about the depth of the fall but the time to recovery. An asset class that bleeds slowly rather than rebounding is telling you something about how the market now regards it.
Her answer is to incorporate risk alongside yield when constructing portfolios, using a disciplined framework that adjusts exposure as market conditions change.
The strategy weights asset classes with risk considerations in mind, manages the portfolio to a volatility target, may raise cash allocations during periods of elevated market stress and can increase exposure when volatility subsides.
This approach aims to reduce the impact of severe drawdowns and avoid emotional decision-making during periods of market turbulence.
As with any risk-managed framework, however, there is a trade-off. By reducing risk after volatility rises and rebuilding exposure gradually as conditions improve, investors may participate less fully in the early stages of a market recovery.
The potential sacrifice in upside capture during rebounds is the price paid for a more disciplined and consistent approach to risk management.
Laurence Parker-Brown is head of content at The Inside Network and managing editor of The Inside Adviser and Investor Strategy News.