Saturday 14th November 2026
Real rates are doing the work behind the surge in long bond yields
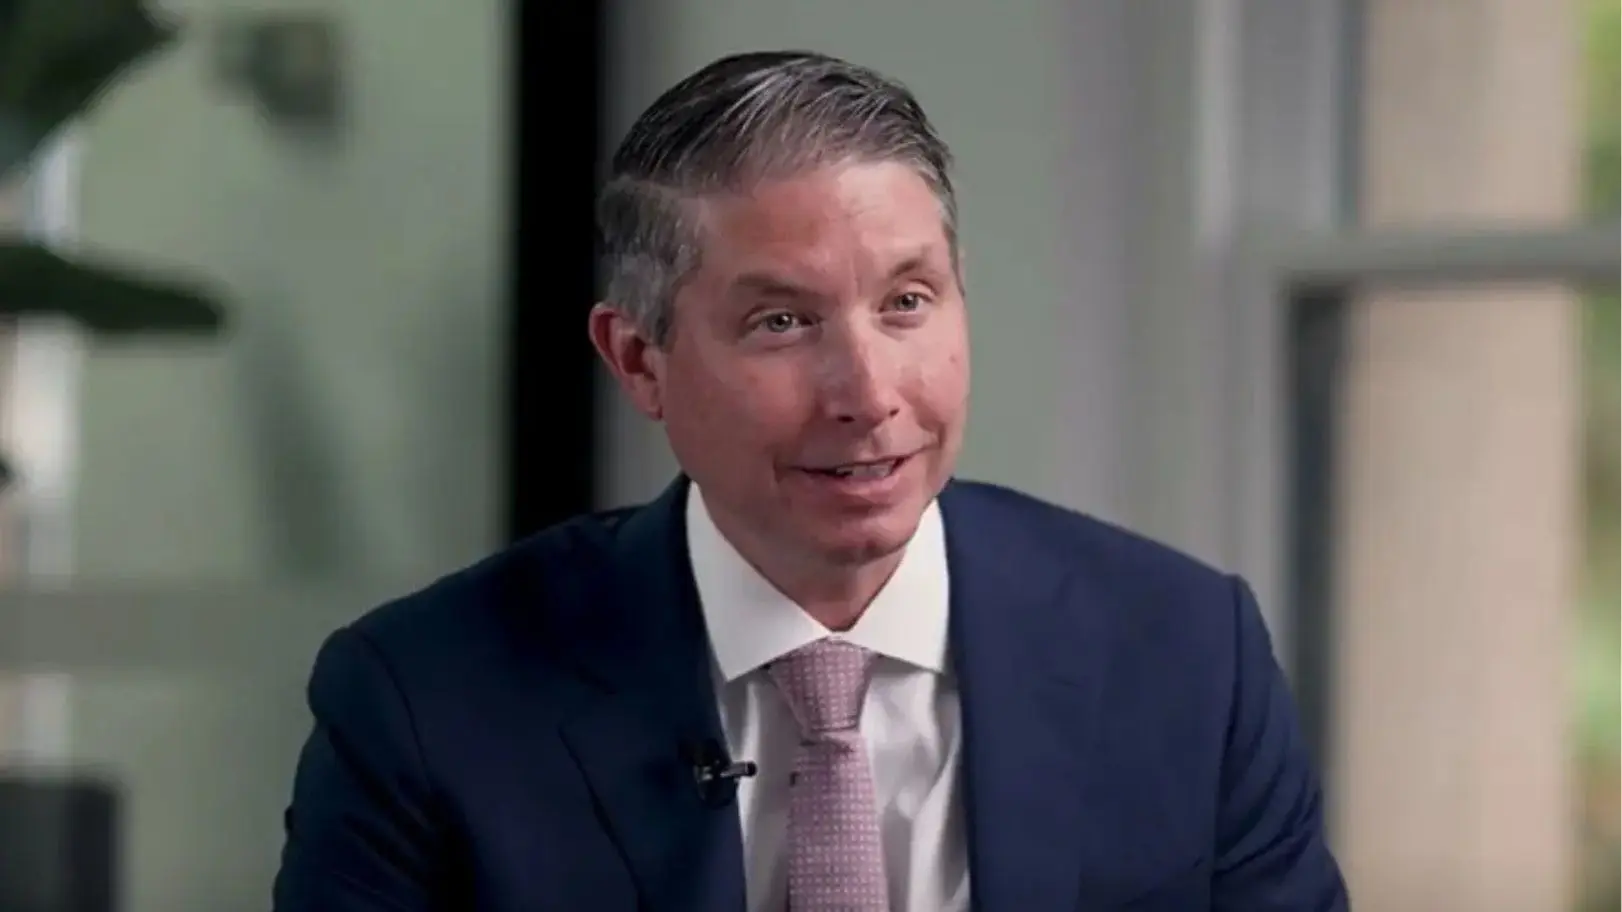
ClearBridge's Jeff Schulze says long bond yields have risen mainly because real rates are climbing, not fiscal fears, arguing yields make more sense measured against strong nominal GDP growth than viewed on their own currently.
Long bond yields climbed through 2026 while the data that usually drives them turned the other way. The US 10-year Treasury yield reached 5.04 per cent on 16 September 2026, its highest level since July 2007. Yet the US Citi Economic Surprise Index and the US Citi Inflation Surprise Index had both rolled over at the end of June 2026, meaning releases stopped beating expectations as often. Softer surprises normally pull yields down rather than push them up.
Jeff Schulze, head of economic and market strategy at ClearBridge Investments, treats that divergence as the question worth answering. He works through the popular explanations first and finds most of them wanting. The weeks since have tested his reading, and it has held.
The supply argument
One explanation blames the weight of new paper. Heavy investment-grade issuance from the hyperscalers has drawn in capital while the supply of Treasuries has risen, so the argument runs that buyers demand more yield to absorb it.
The market has known about that pipeline for months, and investment-grade spreads have traded near their tightest levels of the cycle throughout. Schulze reads that as evidence demand has kept pace with the issuance rather than buckling under it.
The credibility argument
The second explanation is darker. It holds that investors are repricing US fiscal sustainability, Federal Reserve independence and the risk of a debased currency. Here the market has left a cleaner trail, and it points the other way.
Longer-dated credit default swap spreads on US Treasury debt were essentially unchanged from late February 2026, when the 10-year yield last traded below 4 per cent. Investors fearing a solvency event would be paying up for that protection. They were not then, and they are not now.
The composition of the move carries the argument. From the late February 2026 lows through to mid-September, real rates accounted for 50 basis points of the rise in long-term Treasury yields. Inflation expectations added 15 basis points and the term premium 17. At roughly 80 basis points the term premium remains moderate by historical standards, having climbed from a very low base.
“Taken together, stable long-term inflation breakeven rates and a still-modest term premium suggest the bond market is not pricing a persistent inflation or credibility shock. Instead, real yields appear to be doing the heavy lifting with economic growth holding up better than expected on the back of a resilient consumer and the AI infrastructure buildout.”
Investors repriced the policy path accordingly. In February 2026 federal funds futures carried multiple cuts, and by September they carried multiple hikes, with the expected federal funds rate for July 2027 up by nearly 135 basis points.
That repricing has run further since. The Federal Reserve lifted its target range to 3.75 to 4.00 per cent in September 2026 and held there on 28 October, with two members dissenting in favour of another increase. By mid-November futures fully priced a December rise. The move Schulze described has extended rather than reversed.
“While there is no single smoking gun behind why real long-bond yields have risen, what does appear clear is that several catalysts are contributing, as opposed to the bond vigilantes riding into town”, he says.
Yields against nominal growth
Schulze argues yields make more sense measured against nominal economic growth than read on their own. Nominal GDP is running near 6 per cent, above a 10-year yield that has traded either side of 5 per cent since September 2026. Third-quarter growth of 3.4 per cent annualised has held that pace, the strongest sustained run in years.
The closest precedent is the 2001 to 2007 expansion, the last multiyear stretch in which nominal GDP growth exceeded 5 per cent. Through its final four years nominal growth held close to 6 per cent, while the 10-year averaged 4.5 per cent and stayed largely between 4 and 5 per cent.
The pattern repeats offshore. Most developed sovereign curves have steepened alongside an improving global growth outlook. When the US, the UK and the eurozone last recorded three-year average nominal growth near present levels, their government bond yields looked much like they do now. Japan is the outlier.
“From this perspective, the global rise in long-bond yields looks less like a market hiccup and more like normalisation following the period of secular stagnation that emerged after the Global Financial Crisis”, Schulze says.
The decade after the crisis brought deleveraging, weak growth, lingering deflation risk and unconventionally loose policy, and central banks have since withdrawn much of the force that held long yields down.
The comparison carries one caution. Investment-grade spreads were trading at their cycle lows in early June 2007 as well, and within weeks the US investment-grade CDX index widened by some 45 basis points.
By late August the Bank for International Settlements recorded credit spreads more than 70 per cent above their early June lows. Tight spreads describe the demand in front of you rather than the demand that arrives after a shock.
Where the next move comes from
The more useful part of the thesis for portfolio construction is what happens when yields turn. Schulze sees a path lower if consumer spending moderates as energy costs and real income pressures build. Inflation expectations remain well anchored, so disinflationary surprises could pull the expected policy path down with them. AI-driven productivity gains could carry growth without reviving inflation.
Those conditions have yet to arrive. October CPI came in above expectations on both the headline and core measures, and the policy path has moved up rather than down. The thesis earns its keep here as a checklist. Schulze names what has to happen before yields turn, which gives advisers something to watch for rather than a date to wait on.
The path carries its own tension, since a consumer slowing enough to bring yields down would also test the earnings backdrop the argument leans on.
Schulze puts the sequencing this way, arguing a decline in yields would ease financial conditions, support valuations and complement a still-solid earnings picture. In that setting, he says, higher rates are unlikely to prove a lasting real problem, and a subsequent decline or even a pause could set the stage for the next leg higher in risk assets.
For advisers rebalancing portfolios, the reading of this move decides the positioning. A bond market pricing a fiscal accident calls for defence. A bond market pricing stronger nominal growth calls for patience, and for duration bought before the turn rather than after it.
Cristina is a contributor and content manager at The Inside Network.