Monday 5th October 2026
Look through the noise: the case for private markets now
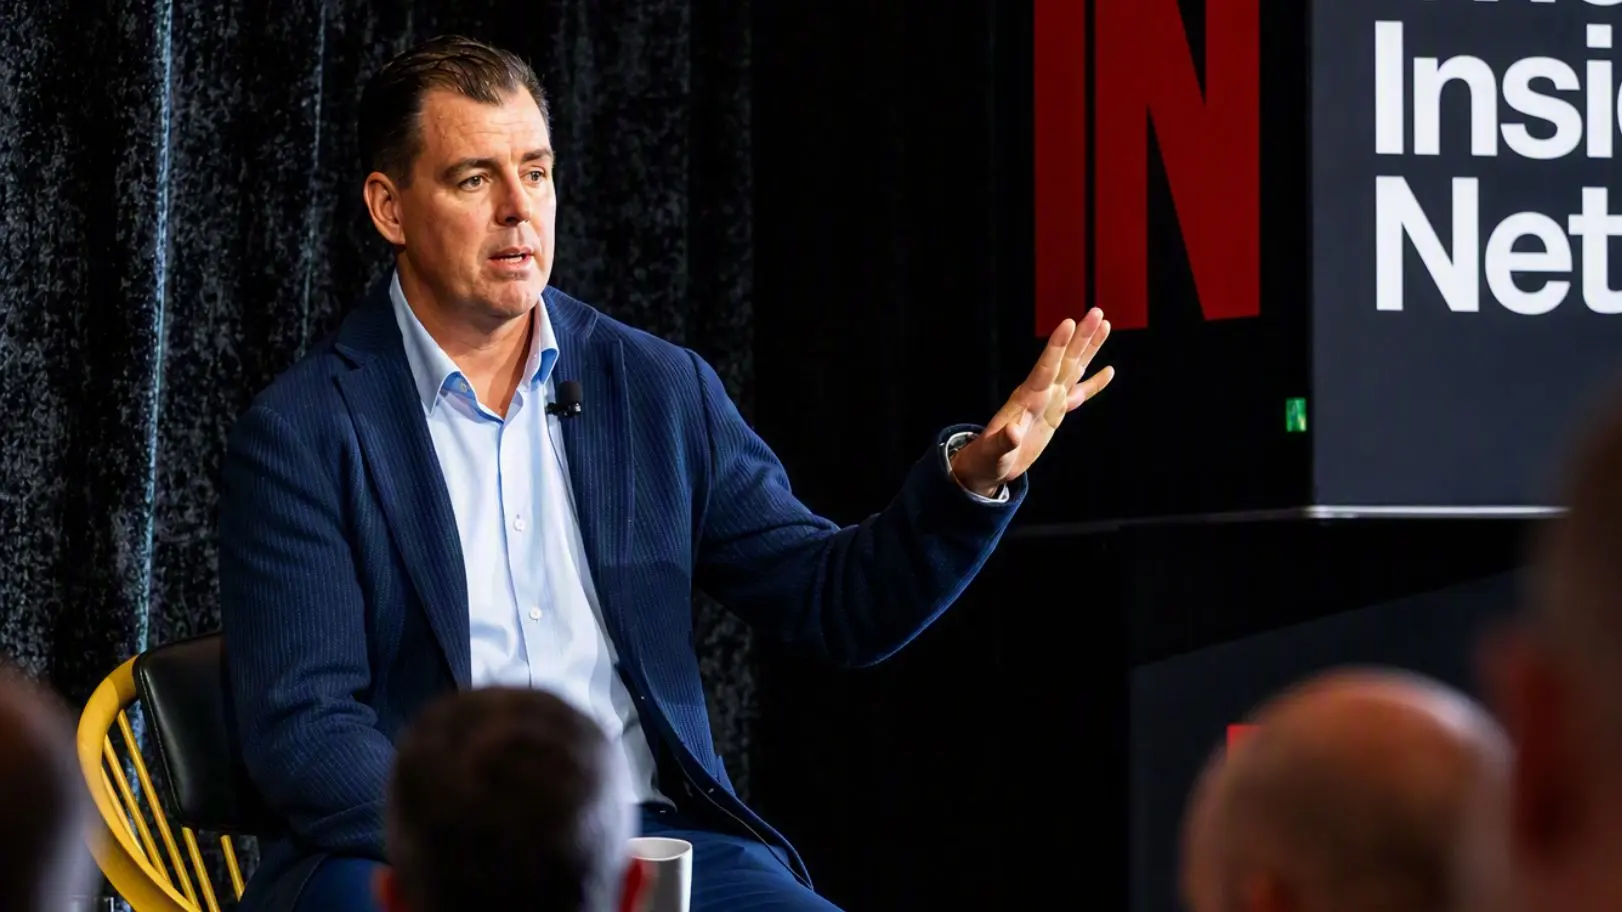
FinCap's Ben Davis says the headlines about gated credit funds and weak private equity marks are drowning out one of the better entry points in years, and that the way to capture it is broad diversification, because gating is the one risk you cannot design away.
The private markets story in the financial press is a worried one. Subdued private equity returns, a shortage of exits, questions over marks, and gating in direct lending funds.
Ben Davis, head of portfolio and investment solutions at FinCap Australia, does not dispute any of it. His argument is that the worry has grown loud enough to bury the opportunity underneath.
Davis calls his read “the quiet turn in private markets,” and the case rests on a simple point about timing. “Most poor returns come from investing at the top,” he says, “and you’re definitely not investing at the top right now if you’re looking at private equity.” The noise, in other words, is doing an adviser a favour.
The entry point
The clearest example sits in private equity. Fund formation in the closed-end space is at a decade low, Davis says, partly because distribution has dried up, which means fewer funds competing for the same deals and better entry pricing for those still deploying.
Mid-market valuations globally look attractive against US mega-cap private equity, echoing a theme that ran through the day.
The 2021 vintage is the cautionary marker. Davis sold a business himself in December 2021, when valuations were near their peak, and the years since have been a long stretch of uninspiring exits. Current pricing is nowhere near those levels, which is precisely the point.
For advisers allocating now, he suggests biasing towards closed-end vehicles deploying capital over the next three years, or evergreen funds still raising, and paying close attention to vintage: a very mature evergreen fund may be drifting into outflow, while newer strategies are putting money to work into the 2026 to 2028 vintages.
Income beyond direct lending
The second opportunity is income, and here Davis is at pains to separate the asset class from its noisiest corner. Some of the US mega-cap direct lenders have gated, and many share exposure to the same assets, but that is not the whole of private credit.
“It’s not all about direct lending,” he says. Listed business development companies, the traded version of private credit funds, are changing hands at 20 to 30 per cent discounts to their unlisted equivalents, and some Australian listed investment trusts trade at discounts too.
Add asset-based lending, real estate debt, core infrastructure, royalties and core real estate, and Davis argues an adviser can build a genuine income book yielding 6 to 10 per cent without relying on direct lending at all.
Real assets round out the case. Infrastructure tends to do well when real rates are high, delivering around 4 per cent a quarter in the top quartile of real-rate environments historically, with the added pull of digital and energy-transition deals.
Real estate, whose fundamentals and cash flows have recovered since the 2022 gating episode, earns its place as a hedge against a growth shock. Davis, who has watched markets for close to three decades, points to the dot-com bust, when the Nasdaq fell 50 to 60 per cent and real estate held up.
With the debate over the AI boom unresolved, he argues that quality matters: if a growth shock arrives, a real estate book is worth holding.
The risk you cannot design out
For all the opportunity, Davis is plain that one risk cannot be engineered away. Gating has already hit US direct lenders, who are further along the wealth-channel cycle, and while Australian vehicles are largely unaffected so far, that is a function of being earlier in the journey, not immunity.
Funds gate by segment, as real estate did in 2022 and direct lending is doing now, which points to a single defence.
“Gating risk isn’t something you can avoid altogether, but broad diversification limits the impact,” he says. An adviser needs an allocation that does not lock up entirely just because one part of it cannot be traded.
The volatility illusion
The collapses of Shield and First Guardian have made platforms slow to add private markets options, and for retail investors those failures are the reference point that any glossy return chart has to answer to. Reported stability is itself partly an illusion: private markets carry what Davis calls artificially low volatility, because assets are marked infrequently.
He recounts the line that “if anyone shows you private markets returns using the smoothed volatility rather than the real, unsmoothed volatility, they’re a fraud,” and says FinCap uses the unsmoothed figures for exactly that reason. The steadiness on the page is not the steadiness an investor would feel in a stress.
None of that is a reason to stay out, on Davis’s reading, but it is a reason to size the exposure with care. Australian wealth portfolios sit at around 2 to 3 per cent in private markets against roughly 20 per cent for endowments, and he thinks 10 to 20 per cent over the next three to five years is a sensible destination, on the view that most clients can tolerate some illiquidity when the bulk of their assets remain in public markets.
The reframing an adviser might make is that private markets are now a whole-portfolio question rather than a single sleeve, with the allocation across the spectrum mattering as much as the choice of any one manager, and that the current noise has improved the entry price rather than closed the door. The discipline is to spread the exposure widely enough that no one gate can trap the lot.
Laurence Parker-Brown is head of content at The Inside Network and managing editor of The Inside Adviser and Investor Strategy News.