Thursday 1st October 2026
Herding: the safest-feeling trade carries the most risk
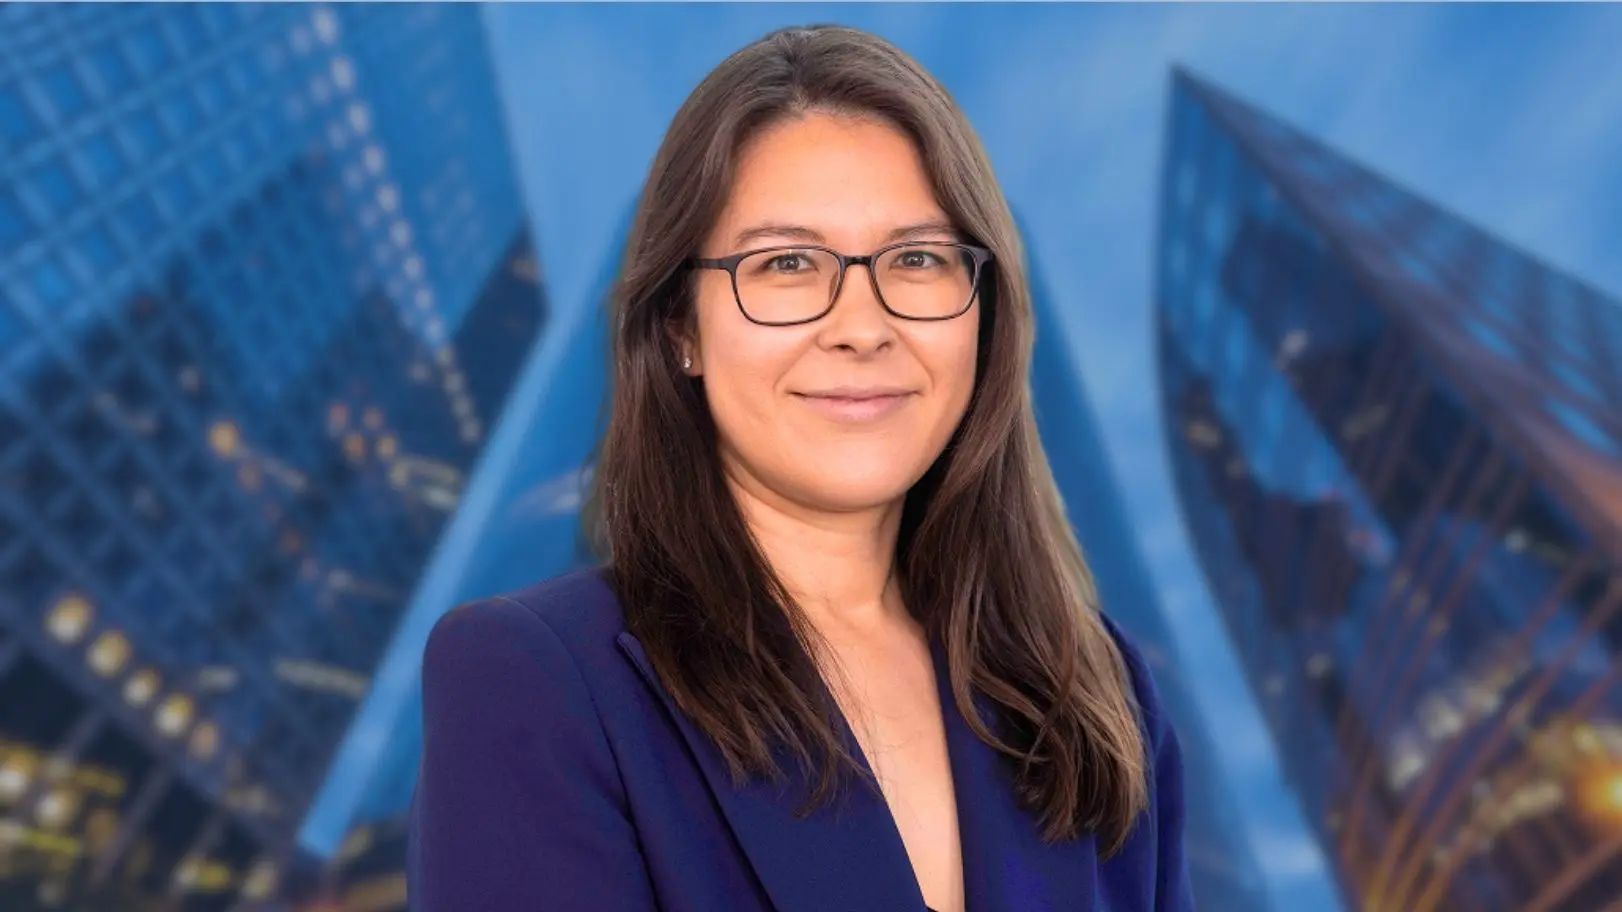
Systematic trend following treats herding as fuel rather than danger, and East Coast Capital Management's Simone Haslinger uses Korea's leveraged ETF crash and gold's slow climb to show why the exit matters most.
Every crowded trade wears a disguise. The more money that piles in, the more the move looks like confirmation, and the more comfortable the position feels to the person holding it.
Simone Haslinger, chief executive of Sydney-based systematic trend following manager East Coast Capital Management, treats that comfort as a warning rather than a reassurance.
Korea has just delivered the demonstration.
What happened in Seoul
The Kospi rose 76 per cent in 2025, then doubled again over the first half of 2026. It broke through 9,300 points intraday for the first time on 19 June. Retail money drove much of the climb, with roughly 78 trillion won (about US$54 billion) flowing into Kospi shares across May and June.
Korea’s first single-stock leveraged ETFs listed in late May, tracking Samsung Electronics and SK Hynix, the two companies that between them make up more than half the index. Buyers could now magnify a bet they had already made.
July ended it with index falling 22.2 per cent, its worst month since October 2008. Circuit breakers tripped four times, a record. SK Hynix lost 35 per cent over the month and Samsung 21 per cent.
ECCM says investors who bought the leveraged ETFs near the top and held to mid-July lost about half their money. Regulators suspended new listings of single-stock leveraged products in mid-July.
Advisers who file this as a Korean retail story will take the wrong lesson from it. Haslinger argues the same behaviour repeats in market after market, and that it has little to do with the sophistication of the investors involved.
The pull of the crowd
Herding is rarely a failure of intelligence. It grows out of a human need for safety, and markets are where that need shows itself in prices.
Devenow and Welch’s 1996 review of the herding literature separates two versions of the behaviour.
Rational herding describes investors copying others because they assume the crowd holds information they lack. Each new buyer supplies a little more apparent confirmation, so the move feeds on itself rather than on fresh evidence.
Irrational herding requires no information at all. Investors follow because following feels safer than standing apart.
Both versions run on the same fuel.
“Being wrong alongside everyone else feels different to being wrong alone, whether or not there’s a good reason for the crowd to be right,” Haslinger says.
That is where the trouble starts for portfolio construction. Comfort and risk travel in opposite directions. By the time a position feels obvious, most of the buyers who were ever going to arrive have arrived, and the marginal seller carries more weight than the marginal buyer.
Two speeds, one pattern
Korea supplied the fast version. “FOMO plus leverage plus a crowded trade is a well-worn combination, and it tends to end the same way,” Haslinger says.
Precious metals supply the slow one. Real forces started the move in gold and silver over 2024 and 2025: central bank buying, rate expectations and currency dynamics. Gold traded around US$4,365 an ounce in mid-August, with silver near US$64.
The story around the move compounds as well. Rising prices attract new buyers, coverage amplifies the narrative, “and at some point the narrative itself becomes a reason to buy, separate from the fundamentals that started it,” she says.
Haslinger thinks the slow version tests advisers harder than the fast one. “This is a genuine multi-year trend, not a single blow-off. That is precisely why it is a better test of discipline than a bubble is.”
Where systematic trend following fits
ECCM runs systematic trend following strategies, so its answer to herding is to ride the crowd early rather than avoid it. “Trend following doesn’t try to avoid crowded trades. It looks for trends early, often before they’re conspicuous, and stays with them as the crowd arrives,” Haslinger says.
“Herding is fuel.”
The buying that carries a trend from early to obvious, and then from obvious to crowded, is what the strategy sets out to capture. Predicting when the crowd shows up matters less than holding the position before it does.
The part worth interrogating is the exit. A systematic model sizes positions on volatility rather than conviction, and closes them when its indicators say the trend has ended. It carries no story it needs to keep believing in order to stay.
“It doesn’t hold on because admitting the trend has turned feels like admitting a mistake,” Haslinger says. “It has no ego invested in being right.”
Where the argument gets tested
Trend following earns its returns in trends and pays for them in chop. Seoul in July shows how that bill arrives. The Kospi rose 17.9 per cent on 31 July, its largest single-day gain on record, in the middle of its worst month since 2008.
A model that cuts exposure on volatility can exit straight into a reversal of that size, then rebuild the position higher. Strung together, false breaks like that are the standard way managed futures programmes bleed through flat years.
Gold pulled back hard from its highs earlier this year before regaining ground in August. Holding a multi-year position through that stretch asked for more patience than most clients volunteer.
The question to put to a systematic manager runs to drawdown length and whipsaw, not only to the crashes the model side-stepped.
Haslinger’s test travels well beyond her own strategy, because it applies to any manager who claims to read a trend: “It’s whether it was there early, and whether it knows how to leave.”
The next crowded trade is already forming somewhere, and it will feel every bit as safe as this one did.
Cristina is a contributor and content manager at The Inside Network.