Thursday 27th August 2026
In private markets, the hard part is now what you build
Coller Capital's private wealth series explores why private markets access is no longer the challenge, and portfolio construction is. It unpacks how secondaries can add diversification, discipline and transparency once evergreen funds open the door.
For a long time, the difficult thing about private markets, at least for Australian wealth firms, was getting a foot in the door. That has changed, with most advisers now putting clients into private markets without much trouble. The difficulty now is what you do once you are there.
This was the subject of a recent conversation hosted by Coller Capital, which describes itself as the world’s largest dedicated private market secondaries manager, as part of its private wealth series.
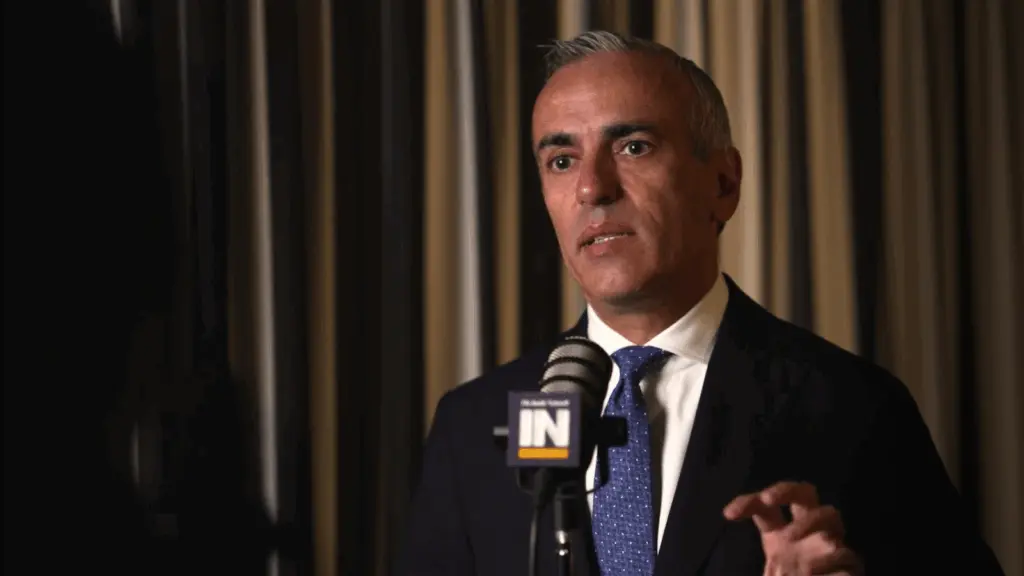
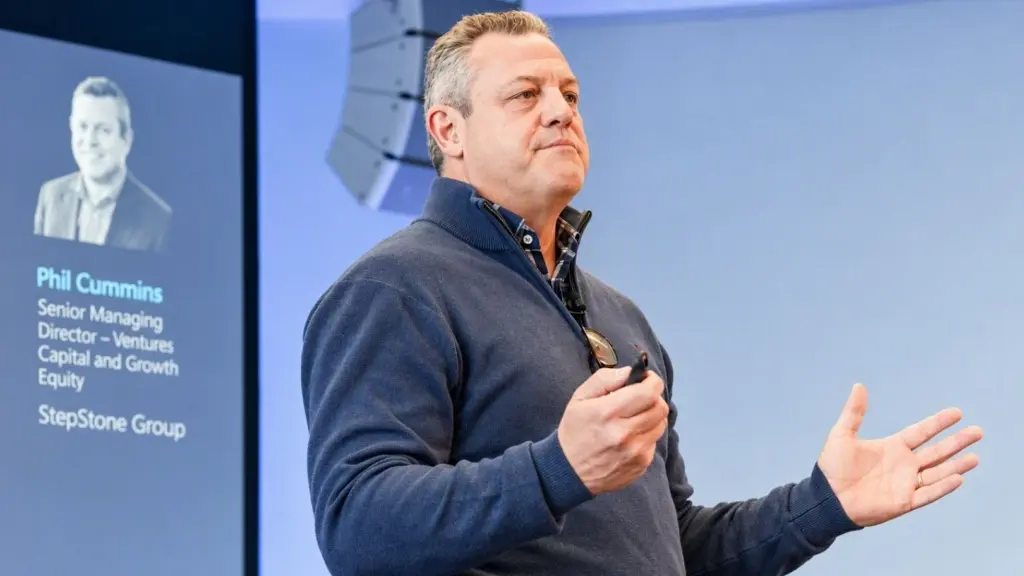
David Hallifax, who heads private wealth for Coller Capital in Australia and New Zealand, spoke with guest Daniel Kelly, chief investment officer at Viola Private Wealth.
The change both men described comes down to structure. Evergreen funds have opened private markets to clients who could not previously get near them, and almost every large global manager now runs one. Advisers are no longer short of options. If anything, they have too many, and that is where the work starts.
“It’s not so much a challenge around accessing private markets today,” Hallifax says. “It’s a challenge around how you actually construct a diversified alternatives portfolio, given the choice you now have.”
Kelly compared it to what happened in music. Recording an album once meant a large contract and expensive studio time.
Now the barriers are gone, and anyone can make a record, he says, “whether they should or not”. He sees the same pattern in his own inbox, full of evergreen funds. Getting access is no longer the problem, but rather working out which managers are any good is.
Getting the basics right
Kelly runs a few basic tests before he looks closely at anyone. He wants to see the people running the money invested alongside their clients, whether through the firm’s balance sheet or their own, and he wants their interests aligned with his. “
If they don’t believe that’s where a marginal dollar should go,” he says, “then we shouldn’t believe that’s where we should be putting one of our clients’ marginal dollars.” Skin in the game, for him, is a condition of entry, not a nice-to-have.
He is also wary of advisers who reach straight for the most interesting idea. His advice is to sort out the basics first. Work out what each asset class is for, decide how much belongs in private equity, private credit and the rest, then find managers you trust to fill those allocations. Secondaries, in his view, are something you add to complement an existing private equity allocation.
Why secondaries, and why now
That thinking is what took Viola to Coller Capital. Kelly wanted a secondaries manager for a particular reason: to spread the kinds of risk his portfolios were carrying.
Because the buyer comes in later in a fund’s life, often from sellers who need to return capital rather than offload weak assets, the exposure is to portfolios further along and easier to see into.
“High-quality portfolios are being sold not because the managers want to sell them, just because they have to return capital to investors,” Kelly says.
Structure is a different skill
He was careful to separate the strategy from the way it is packaged. Running an evergreen fund that offers clients regular liquidity is a different job to running a traditional closed-ended one, and being good at the first does not make you good at the second.
“Just because you’re a good private equity manager doesn’t mean you can manage a liquidity sleeve.”
Viola would only use an open-ended structure with a firm it trusted to run it properly, and Kelly says Coller meets that test.
Kelly talked about the firm’s openness, the strength of its balance sheet and the effort it puts into explaining the market. “You’re transparent, you’re timely, you’re always available,” he says. “We want to form long-term, enduring relationships with firms like yours.”
Hallifax pointed to something that sets Coller apart. Because it specialises in secondaries, the firm works both sides of the market, buying LP positions from institutions and acting as a manager in its own right.
That, he says, is one reason it puts so much into education. Through its secondaries institute, Coller sets out to explain what secondaries are, how they work and why they matter now.
The client conversation
Kelly finds the idea easy enough to explain once clients have the right picture. Every market has a primary and a secondary side, he says, and investors already understand this from shares.
“We’re not giving you an equity allocation by buying every IPO.” Property is the same. Selling a house does not mean there is anything wrong with the house. Usually, it just means the owner has found something else to do with the money.
What came through was simple enough. Secondaries have gone from an institutional niche to a normal part of how good portfolios are put together.
Getting clients into private markets is the easy part these days. Building that exposure well, with the right manager, is what matters most.
Cristina is a contributor and content manager at The Inside Network.