Thursday 17th September 2026
Evergreen infrastructure: why the redemption terms deserve a closer read than the return target
I Squared Capital launches an evergreen private infrastructure fund for Australian wholesale clients, as advisers weigh redemption caps and valuation lags against the asset class's yield, inflation-linked income and long-term growth appeal for client portfolios.
Australian superannuation funds hold roughly A$206 billion in unlisted infrastructure, according to figures the Association of Superannuation Funds of Australia published in March, drawing on APRA data to September 2025. Private clients hold a rounding error by comparison.
The reason has less to do with appetite than plumbing as infrastructure traded through closed-end funds with 10-year lockups, capital calls and institutional minimums. All that machinery never suited a client who might need money back inside a decade.
Managers have spent the past three years rebuilding the machinery. I Squared Capital became the latest to do so this week, opening its OpenInfra private wealth platform in Australia through the ISQ OpenInfra AUT Fund, an evergreen Australian unit trust available to wholesale clients.
The firm also appointed Linda Stangherlin as a director, investor relations, to lead distribution across the region. Sydney-based, she brings more than 20 years across investment management and wealth, with a background in alternatives, portfolio construction and adviser engagement.
I Squared manages more than A$85 billion (US$60 billion) as at the first quarter of 2026, across a portfolio of more than 100 companies. It launched in 2012 and has stayed narrow, investing only in infrastructure and concentrating on the middle market.
What the asset class promises
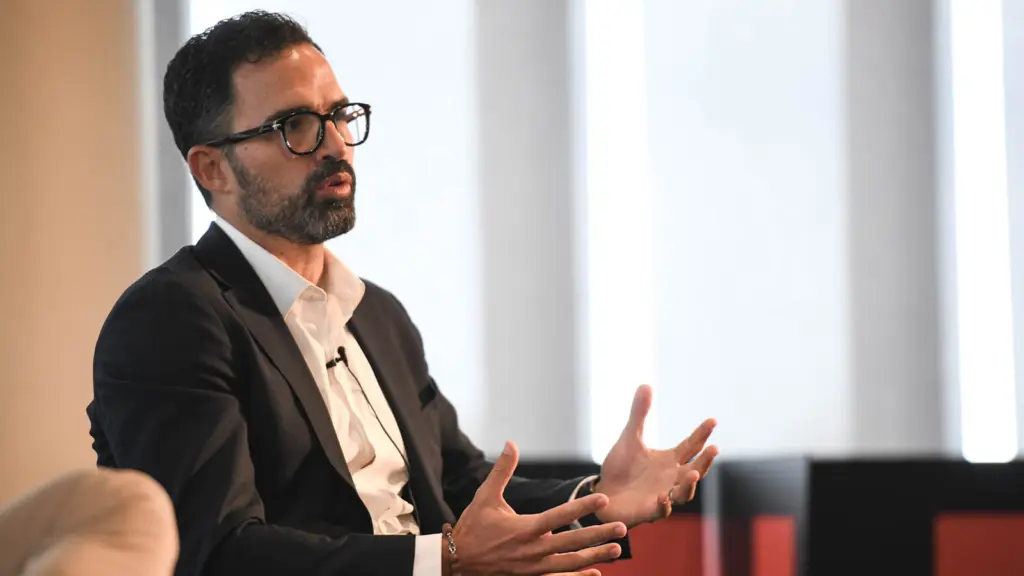
Gautam Bhandari, co-founder, global chief investment officer and managing partner at I Squared, frames the opportunity around public balance sheets and power demand:
“We believe that we are in the early stages of a global infrastructure supercycle.”
His argument runs that indebted governments cannot fund what needs building, and that artificial intelligence and essential services now demand capital on a scale private markets have to supply.
For investors, he says, “infrastructure offers a middle ground that can offer equity upside, credit-like yield and real assets with inflation-linked revenues”.
That middle ground is worth unpacking for clients, because it comes from three separate places. Contracted or regulated revenue produces the yield.
Pricing formulas tied to CPI produce the inflation link. Growth in the underlying business produces the equity component. A regulated water utility leans heavily on the first two.
A merchant data centre leans on the third, and carries technology obsolescence and tenant concentration risks a water utility never faces.
Both assets carry the infrastructure label. Telling a client they own infrastructure describes the wrapper, not the exposure, so the portfolio disclosure in the information memorandum deserves more attention than the return target printed above it.
The structure is the change, not the asset
Evergreen funds work differently from the closed-end vehicles that built this asset class. They take subscriptions continuously, process redemption requests on a set cycle, and strike a unit price from periodic independent valuations rather than from a market. That solves the lock-up problem. It creates two others.
The first shows up in a crowd. Redemption caps exist so that a fund can protect the portfolio instead of liquidating assets at whatever price a forced seller gets. They work as designed, which means they bind precisely when clients want out together.
Blackstone’s US non-traded property trust reached its withdrawal limits in late 2022 and rationed redemptions for months. Investors who read the cap as a formality learnt otherwise.
The second shows up in the pricing. Appraisal-based valuations move slowly by construction. When bond yields climbed through 2022, listed infrastructure repriced within months while unlisted valuations took far longer to reflect the same change in discount rates.
Reported volatility looks lower as a result, and some of that smoothness is real diversification while some of it is just the lag. Advisers who build portfolios off standard deviation inputs should know which portion they are relying on.
None of this argues against the allocation. It argues for reading the redemption frequency, the cap, the gating provisions, the valuation cycle, the identity of the valuer and the fee crystallisation terms before signing anything.
Adviser demand is running ahead of adviser allocation
I Squared’s own research, the ISQ OpenInfra Index, surveyed hundreds of financial advisers working with alternatives and found private infrastructure among the most sought-after allocations in the private wealth market.
Three quarters of advisers told the survey they expect to lift private infrastructure exposure by 2027, and an equal share said they would rather build that exposure with a specialist infrastructure manager than a diversified alternatives house. The index draws on Praemium and Fidante adviser survey work published between 2025 and 2026.
Preference for specialists makes sense in an asset class where operating capability drives returns. It also raises the bar on manager selection, because a specialist with a short track record offers concentration without the compensating experience.
The wholesale test is doing the gatekeeping
The fund is open only to wholesale clients under section 761G of the Corporations Act. Those thresholds, $2.5 million in net assets or $250,000 in gross income across two consecutive years, have not moved since 2001, and asset price growth has quietly pulled a large number of ordinary retirees inside them.
A client can clear the test on paper and still hold the wrong liquidity profile for a semi-liquid fund. Position sizing carries more weight here than eligibility.
The local record to interrogate
I Squared has worked with Australian institutions since 2014, counting superannuation funds, sovereign wealth funds and insurers among its partners. It opened a Sydney office in 2022 and has since committed more than A$2.1 billion (US$1.5 billion) to businesses operating here, including ANZA Power in renewables, Octa in energy transition, SoilCo in organic waste processing and Rentco in heavy-duty transport rental equipment.
Irina Zilbergleyt, managing director and global head of distribution and product strategy for OpenInfra, says the Australian launch “builds on I Squared’s longstanding presence in the Australian market”.
Those local commitments demonstrate the firm can source and operate assets in this market. They do not tell an adviser what the AUT fund itself holds, and the two questions are separate. Ask for the current portfolio, the ramp-up schedule and how much of the trust is expected to hold cash while it deploys.
Evergreen infrastructure funds will keep landing on approved product lists through the next 12 months. The decision that clients eventually feel has little to do with whether to take the meeting. It comes down to what the allocation replaces, and whether the money funding it can afford to stay put through a quarter when everybody else wants theirs back.
Cristina is a contributor and content manager at The Inside Network.