Monday 5th October 2026
How to treat the SPIVA scorecard as a portfolio construction tool, not a verdict
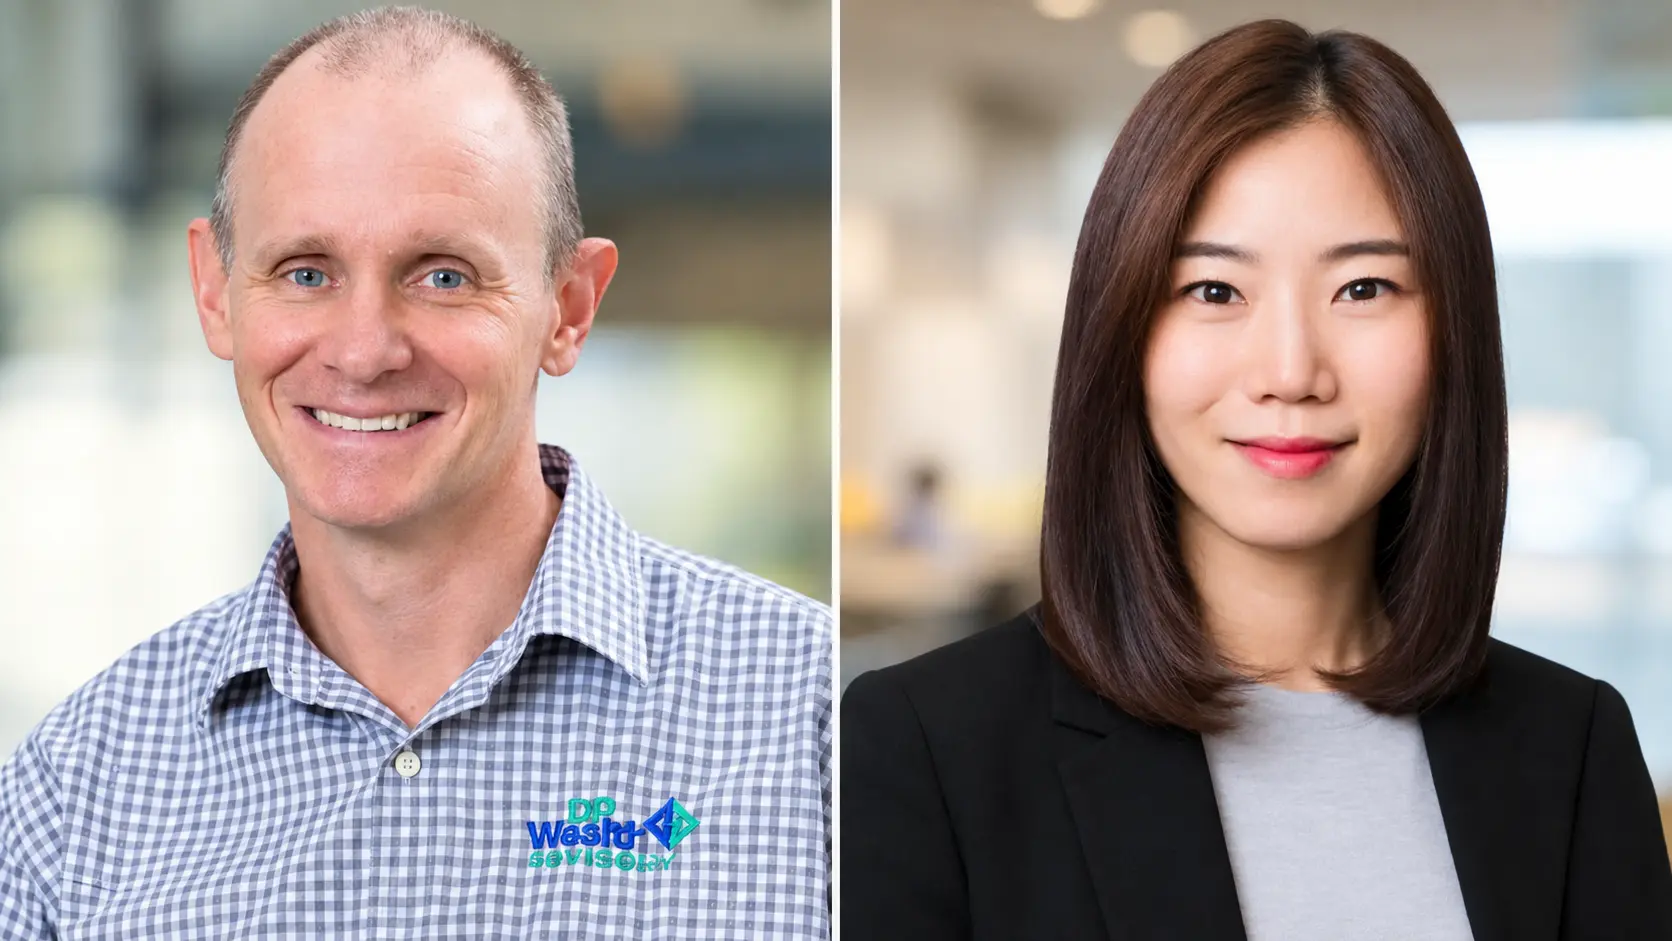
Andrew Wielandt, director at DP Wealth Advisory, says the latest SPIVA Australia data reinforces a core and satellite approach he has run since attending a US study tour in 2018, using low-cost passive exposure as the default and active management as the exception he has to justify.
Most advisers who follow the SPIVA scorecard nod along at the headline number and move on. Andrew Wielandt, director at DP Wealth Advisory, builds his portfolios around it.
The mid-year 2026 SPIVA Australia scorecard from S&P Dow Jones Indices found that 78 per cent of Australian general equity funds failed to beat the S&P/ASX 200 in the first half, the second-worst result since the study began in 2013.
Wielandt has been watching that pattern for years, and it shapes how he splits money between passive and active exposure before a client conversation even starts.
“SPIVA highlights that some markets are highly efficient, making it very difficult for active managers to consistently outperform after fees,” Wielandt says. “It also helps with our core investment philosophy of a low cost passive core supplemented with a higher cost, active satellite exposure.”
A framework, not a verdict
The distinction matters. Wielandt is not reading the scorecard as a case against active management altogether. He treats it as a way of deciding where a manager has to clear a higher bar before the extra fee is worth paying, and where a low-cost index fund is the harder position to beat.
“To me, SPIVA simply tells me what is the benefit of active management over the short and long term when looking at investing,” he says.
That question looks different by asset class. The scorecard’s own data backs the split.
Australian bonds remain the one category where a slim majority of active managers still beat their benchmark, even as that margin narrowed sharply this year, while large-cap Australian equities, where the top 20 stocks now make up about 64 per cent of the index, have been the hardest category for active managers to clear in over a decade of the study.
“Each report has different asset classes where active management is adding value over the shorter term, given the market noise at the time,” Wielandt says.
One stock can decide a category
The scorecard’s Australian A-REIT data shows why that category-by-category read matters more than a single headline figure. Goodman Group now makes up close to 40 per cent of the Australian A-REIT index, and S&P Dow Jones Indices’ Sue Lee, who compiles the scorecard, says that single holding has significant impact on the category’s result in recent years.
“How the active funds’ broadly performed really depends on how they were positioned against this one stock,” Lee says.
Goodman underperformed in the first half, and the funds that underweighted it were likely the ones that outperformed. It is the kind of detail a headline underperformance number cannot answer on its own, which is presumably why Wielandt reads the scorecard category by category rather than off the top line.
Persistence of skill
The scorecard’s persistence data lands hardest for him. Active funds that outperformed for five years to December 2020 were more likely to fall to the bottom quartile in the following period than to stay at the top, which highlighted the difficulty in finding outperforming funds in advance.
“As usual, when we look to the persistence of long-term outperformance, the longer the time frame, the harder it is for active managers to outperform the market, again reinforcing the benefits of a core and satellite approach to portfolio construction,” Wielandt says.
That data has an obvious limit. It says nothing about a specific manager a client already holds, only about the odds facing the category as a whole, and Wielandt’s own answers do not pretend otherwise.
A core and satellite structure is still a bet that a chosen satellite manager can do what most of their peers could not, and the same scorecard that justifies the passive core is the one warning that most active bets fail to repeat.
“It’s an important tool to help clients determine the value of active investing,” Wielandt says, and that is the more modest claim the data supports. It tells him which markets are efficient enough that a client is usually better off paying less for the index, not which fund will outperform next.
Laurence Parker-Brown is head of content at The Inside Network and managing editor of The Inside Adviser and Investor Strategy News.