Thursday 15th October 2026
Building portfolios for life’s dry seasons
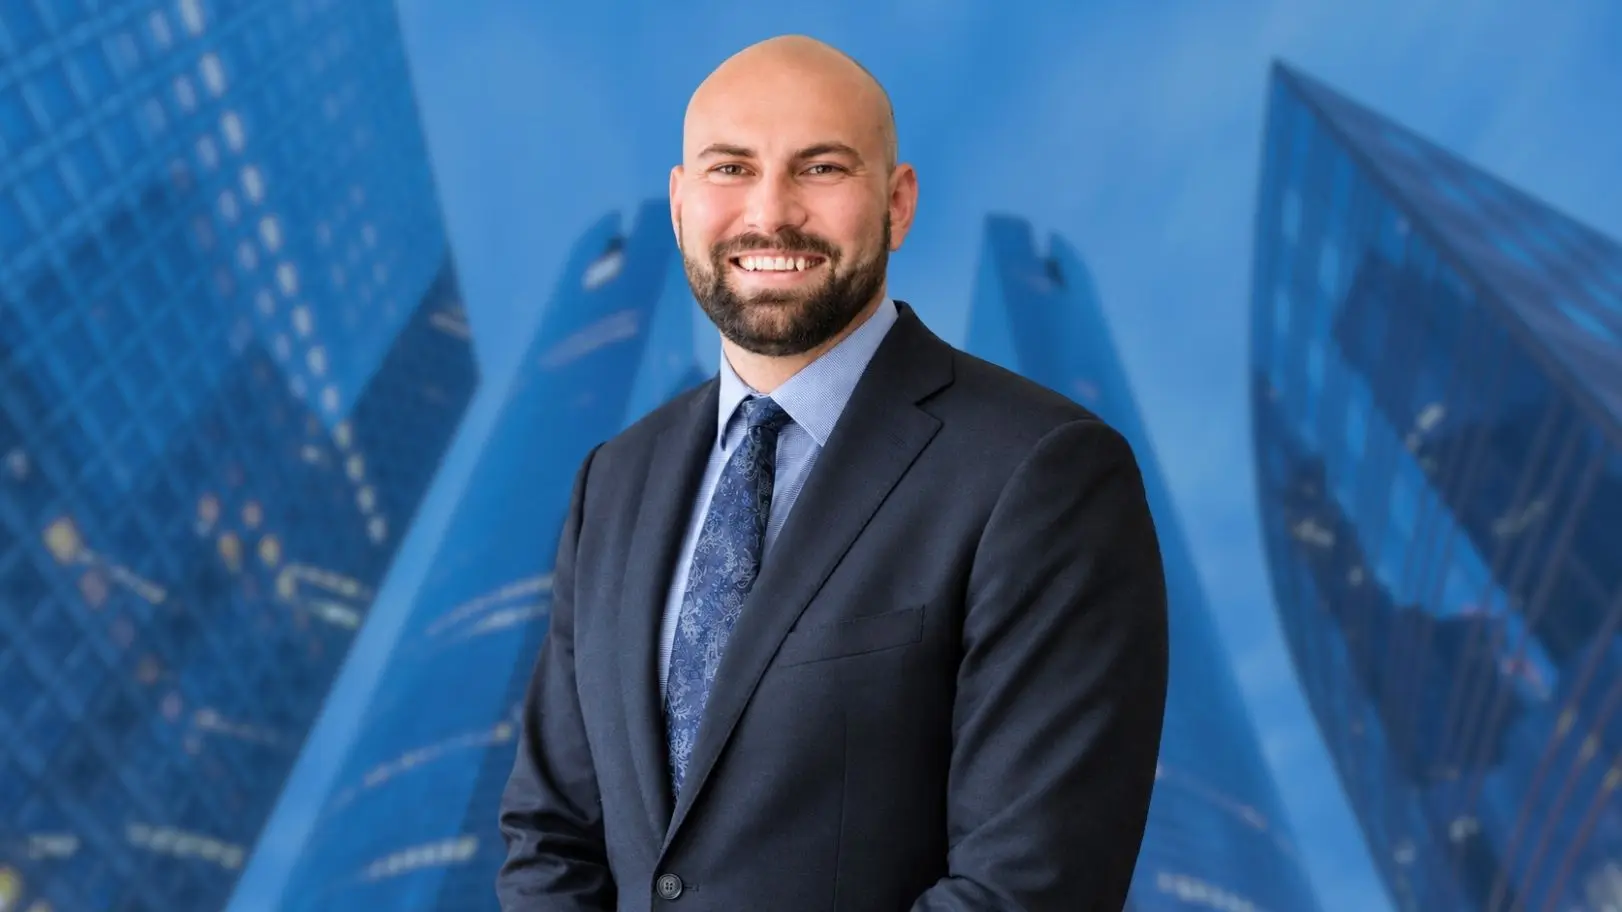
Troy Armstrong, founder and senior adviser at Larapinta Private, builds outside-super portfolios around a question his farming clients know well: how quickly can you reach your money when the season turns?
Every farmer knows the rain keeps no timetable, while the bills arrive like clockwork. Troy Armstrong has spent more than two decades advising families who live by that rule.
As founder and senior adviser at Larapinta Private, he works with regional, agricultural and pastoral families. The lessons of the land shape how he invests the money they hold outside superannuation.
“You don’t know when they’re coming, and you don’t know the drought has hit until it has already hit,” he says of the unexpected events that can upend a family’s plans.
For his clients, that reserve carries a plain-spoken name. Armstrong calls it, simply, “the drought money”. It exists for the weather event that can wipe out a season, and for the costs that follow when children leave the farm for boarding school and university.
The principle travels well beyond the farm gate, and it offers a useful lens for any adviser whose clients face large, unpredictable calls on their capital.
When the business is the nest egg
Armstrong sees the same pattern among small business owners, whose wealth often lives in bricks, machinery and dirt.
“It’s the typical small business owner whose superannuation is in the land, the factory, or whatever the business operates from,” he explains.
When those clients eventually sell, the proceeds can far exceed what the contribution rules allow into super. “Hopefully, in most cases, when you liquidate that factory or parcel of land, it’s quite a large amount, and you’re not going to get it all into super,” he says.
For many years, the default home for wealth that could not enter super was a family trust. Policy proposals affecting trusts have made that choice less clear-cut, so Armstrong works through the options alongside each client’s accountant. He takes a calm approach to the uncertainty.
“You don’t jump at shadows,” he says. Whatever structure holds the money, his conviction stays firm. “Keeping money highly liquid outside super is, I think, a must,” he says.
Most advisers know the client who rings after buying a house at the weekend, needing a couple of million in a hurry. Super offers little room to respond to that call.
How liquid is liquid enough?
Armstrong sets a demanding standard, aiming for 80 per cent of an outside-super portfolio to be redeemable within 10 days, and the whole portfolio within a month. The target serves peace of mind as much as any extreme scenario, because it “helps some of these families sleep a bit better at night, knowing they can get quick access.”
He scales the target to the size of the pool. “If you’re talking tens of millions, you probably don’t need that much liquid,” he says. “But if it’s the extra couple of hundred grand they’ve saved over the last few years when the years have been good, you want to keep that as liquid as possible.”
That standard steers him towards listed and daily-priced investments, because “public markets are still the only way to access fast liquidity.”
Fixed income funds carry much of the income load, supported by dividend-focused Australian equity funds. He keeps growth exposures light for a practical reason. “We don’t want too much capital gain floating through,” he says.
Private credit earns a more cautious place in his thinking. Armstrong remembers the global financial crisis, when property trusts froze and investors waited two years for their money. “That’s a situation I didn’t want to be in again,” he says.
If liquid fixed income delivers seven to nine per cent, he wants private credit “to give me at least 300 basis points over”. When investors give up access, he argues, “we should be demanding a bit more before we go in.”
No magic formula
Armstrong does not build liquidity around a neat list of known expenses. “People know what some future liquidity events may be, but you also have to have that black swan money,” he says.
With farming clients, he starts with a concrete scenario. “I talk around what it would look like if there was a season where you had to buy in feed for the whole year. Let’s structure it around that.”
He also builds in a healthy margin for error. Clients tend to underestimate what lies ahead, so he rounds their estimates up as a matter of habit. “If boarding school is going to be $100,000 for Years 11 and 12, I think, that sounds like 150,” he says.
“In my book, it’s a much easier conversation as an adviser to say, ‘We’ve had too much in liquid options, and you could have earned 10, but you earned 9,’ than, ‘Sorry, you’re going to have to wait six months for the rest of this money.’”
Fair, equal and the next generation
Succession weighs heavily on agricultural families, where the farm often passes to one child while siblings build lives elsewhere. Armstrong sees investment bonds as a useful tool here.
“The beauty I see in investment bonds, and the aspect I look at the most, is this outside-estate asset that can pass on as an estate asset, to a degree, without going through that contestability,” he says. “I talk to a lot of our farming families about what is fair versus what is equal in the way an eventual estate may split.”
Younger clients deserve a place in this conversation too, though household budgets come first. For accumulators, the challenge lies in “finding the excess money and surplus cash flow”.
Where a surplus exists, he sees merit in an investment bond, while reminding clients of the 125 per cent contribution rule. “If you put in $10,000 this year, you can’t do $20,000 next year,” he explains.
For Armstrong, the drought money is more than a planning concept. He keeps reserves liquid “for the eventual tap on the shoulder, and I say that from my own experience.”
Every client, on the land or off it, faces a dry season of some kind. His role is to make sure that when it comes, the money is already within reach.
Cristina is a contributor and content manager at The Inside Network.