Monday 2nd November 2026
Who repays the loan is the key distinction that matters in credit
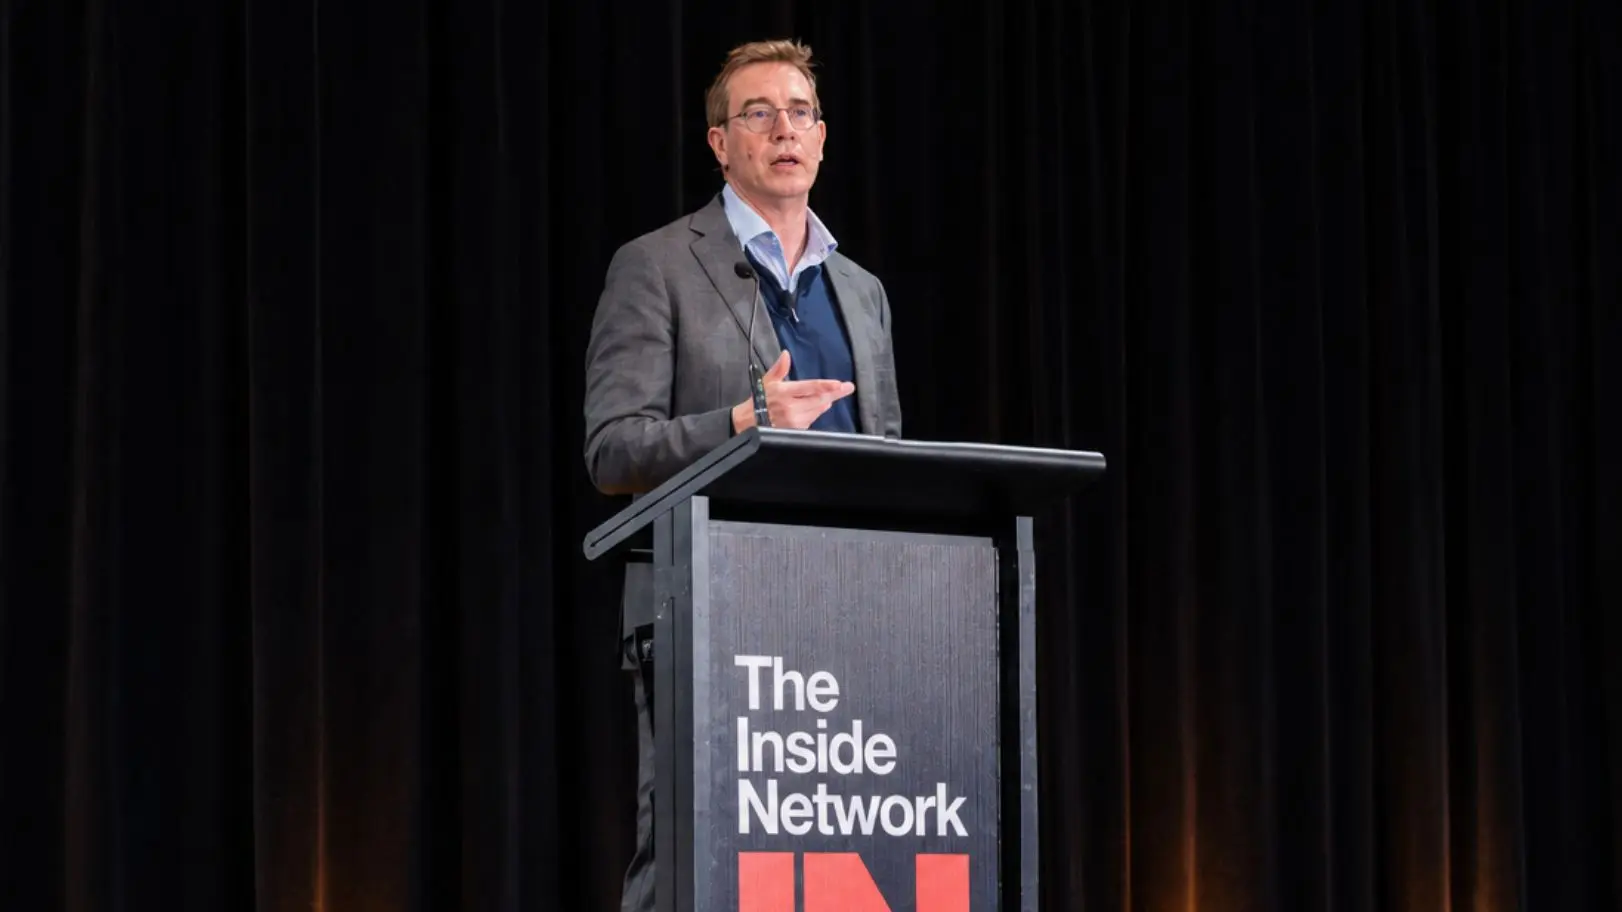
Remara’s Gwion Moore says concern about US private credit can spill over into Australian asset-backed lending, even though the two lend against entirely different things. One is repaid by a company’s earnings and its ability to refinance, the other by many small borrowers and the assets securing them.
Credit investments are often discussed as though they represent a single, comparable category. In practice, the underlying exposures can be very different. The more useful question for investors is what ultimately repays the loan.
For Gwion Moore, chief investment officer at Remara, the starting point for assessing any lending strategy is straightforward. Understand what is expected to repay the loan, and how resilient that source of repayment may be across different conditions.
That distinction informs everything from portfolio construction and diversification to the appropriate level of return, the role of collateral and the protections available to investors. It also provides a more useful basis for comparison than broad labels alone.
Moore came to the non-bank lender from the institutional side, having run investment strategy at Mercer across roughly $30 billion of superannuation assets and held a similar role at Suncorp looking after insurance assets. Remara has been operating since 2019 and has had credit funds open to the public for about four years.
Repayments
The corporate challenges experienced in the US has specific characteristics that differ from local asset backed lending. Lenders extended much of the credit that caused the concern against earnings. Much of it went to highly geared vehicles owned by private equity. In those vehicles, the exit is either a sale of the business or a refinancing of the loan.
When artificial intelligence repriced parts of the software and technology sector, the earnings forecasts underpinning those loans moved, and a loan repaid by earnings has nowhere else to go.
Australian asset-backed lending is repaid through completely different drivers. The money comes from thousands of small borrowers paying down loans secured against something, with the pools often over-collateralised, which is a materially different exposure from a single company’s fortunes.
Remara originates across eight or nine lines, covering vehicles, equipment, housing and construction, and has been building positions in less crowded corners. Novated leasing packages a car through salary sacrifice, with the vehicle as collateral.
Insurance premium finance funds a business’s annual premiums upfront and collects repayment over the year, and if a borrower defaults the lender can cancel the policy and reclaim the unused premium.
The structure
The plumbing is where the due diligence is crucial. Loans are aggregated in a warehouse whose senior note is typically bought by a major bank, which brings that bank’s own credit work to bear on the structure.
Remara works with the likes of Westpac, National Australia Bank, Barclays and JP Morgan as its warehouse providers. The pools are self-amortising, with principal repaid through the life of the loan rather than in a lump at the end, and new loans written continuously as old ones run off, which keeps the weighted average life of a book to two or three years.
The structure then divides cash flows, with the senior tranche receiving payment first, the mezzanine next and the first loss or equity tranche taking what remains. Losses run in the opposite direction, hitting the equity tranche before anything reaches the tiers above it, and that is where Moore says investors should put the question.
“If you’re considering investing in asset-backed securities, you should expect your originators to keep a portion, at least, of that first loss, to make sure that their economic interests are aligned with those of the investors.”
Volatility and what it hides
Asset-backed securities are floating rate notes priced against bank bill rates, so they carry little interest rate risk, and the short life of the underlying loans means even a meaningful widening in credit spreads moves the capital value only modestly.
Moore puts investment grade asset-backed paper at around 7.5 per cent, some 250 to 300 basis points over cash, with returns running out to 1,000 basis points over cash further down the capital structure and a commensurate rise in risk.
He is also clear about what the smooth line conceals, since private assets do not show their volatility and the real question is how expected credit losses compare with realised ones.
The same self-amortising structure that limits mark-to-market movement also means a deterioration in arrears feeds through to returns quickly, and the collateral only does its job if recovery values hold. Used vehicle prices and construction asset values both fall in the conditions that cause defaults to rise, which is precisely when investors rely on the protection.
Moore’s own point about concentration matters here too. Residential mortgages dominate Australian asset-backed issuance, and construction finance dominates the local private credit market, so a portfolio built from the obvious names can end up holding one economic exposure twice.
The compensating factor is visibility. An Australian-only lender sees arrears and extensions in its own loan book as they happen and can adjust origination in response, and the legal position is simpler than in a market with 50 separate jurisdictions. “Australia is a well-run country. It has a favourable environment for creditors,” Moore says.
The relevant test is whether the underlying loan portfolio, its diversification and its structural protections continue to perform as intended across a range of credit conditions.
Laurence Parker-Brown is head of content at The Inside Network and managing editor of The Inside Adviser and Investor Strategy News.