Monday 12th October 2026
Inside the private technology class
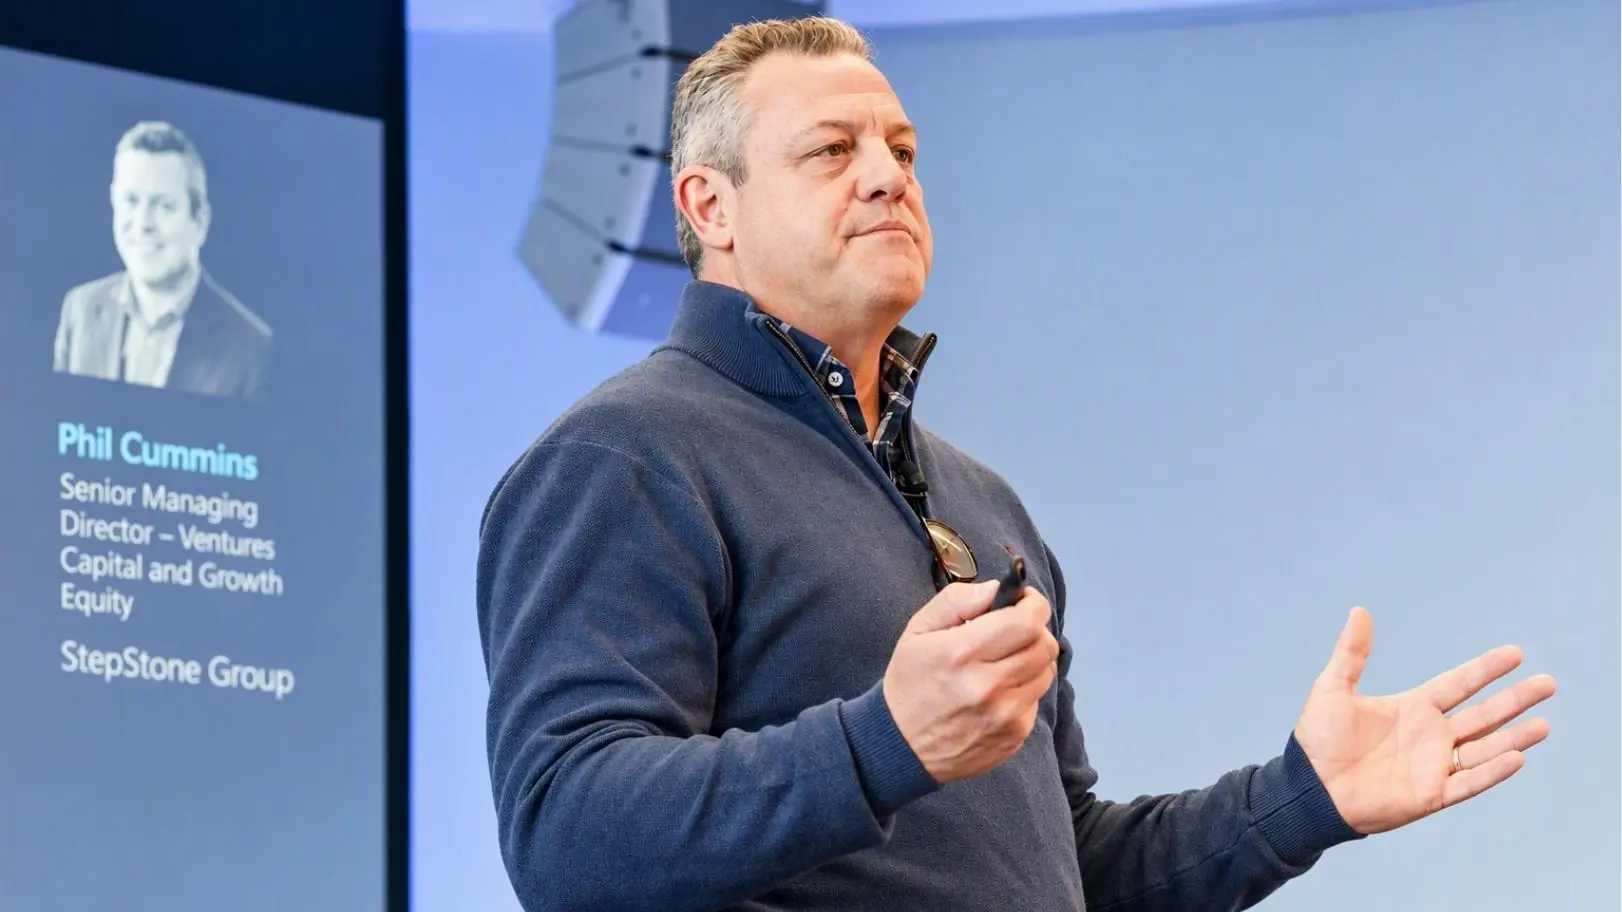
StepStone Group’s Phil Cummins says the label venture capital now describes companies worth tens or hundreds of billions that have no need to list, and that advisers seeking technology equity exposure cannot get it from public markets alone.
The two leading artificial intelligence model companies in the world are both private. These companies have been able to raise hundreds of billions of dollars in the private markets reversing how the last technology cycle worked and leaving anyone building equity exposure with a gap the listed market cannot fill.
“If people are looking for equity exposure, particularly around technology and equity risk, you simply cannot ignore the private market component.”
Phil Cummins, senior managing director at StepStone Group, is careful about the label. Venture capital implies early-stage risk on unproven companies, which is not what the category mostly holds now.
The edge of innovation has always sat in private markets; what has changed is that private capital can fund a company to a far later stage, so the scale reached before listing is unlike previous cycles.
A new architecture
Cummins frames the four decades from the desktop to the peak of software as a service in 2022 as one cycle, built on a single architecture: classical computing and deterministic software, which produced the largest companies in the world today.
What is arriving now is not an acceleration of that, but a different architecture. “We spent decades digitising workflows, and what is happening now is that the compute performs those workflows.”
That distinction justifies committing the capital, which Cummins compares in scale to the railways and electrification rather than any technology cycle since. He treats the tension between that build-out and the bubble question as healthy, and thinks the build is still early.
Another observation core to this thesis is the pace of development. What changed in the past 90 days is not which model is ahead, a debate he considers largely irrelevant, but the volume of tokens consumed, while penetration stays low and the application layer has not begun to expand.
Where the value lands
The unanswered question is which layer of the supply chain captures the economics. This is a three-and-a-half to four-year story since ChatGPT arrived, and the accepted answer has already changed several times.
At the model layer he expects a durable market in premium tokens at the frontier of intelligence. He points to markets such as life sciences, materials science and complex engineering rather than everyday queries, where providers can price intelligence well below the value it creates and still remain highly profitable.
Below that, StepStone is more constructive on compute. If you were designing computing for AI from scratch, Cummins argues, you would not arrive at what Nvidia built. It was the best available approach at the time, which tells you the industry is still inventing the layer. That is generating activity in power, including small modular reactors and next-generation nuclear fuels, and in cooling, wiring, optical connections and chip design.
His example is Etched, which builds an application-specific chip for inference, the work done when a query runs against a model. StepStone backed the company last year at a couple of billion dollars. Cummins says it has since raised at $20 billion, and he expects it to become a $100 billion company.
Bottlenecks move around that supply chain, which is why he is careful about forecasts.
“Anyone who says they know what this looks like in five years is probably not going to be accurate.”
Bits back to atoms
The layer Cummins thinks is least understood is the physical one. The previous cycle turned analogue processes into bits, and software, having won, largely lost its pricing power. What follows might just be the reverse: compute reaching back into real-world industries.
Robotics carries most of that hope. Defence technology, on his reading, is really a story about autonomy and automation, software enabled hardware effecting actions in the physical environment. Advanced manufacturing is active, and mining is being rebuilt around full-stack AI operations.
Automation and autonomy of this kind augments physical labour rather than replacing it, he says, and runs into the onshoring argument, since work outsourced for decades on cheap labour can return with a smaller, more skilled workforce.
What the marks mean
Perhaps the harder question is what a private valuation represents. Cummins is matter-of-fact about it: private market valuation is a well-trodden path, governed by accounting standards, reviewed and audited, and not the improvisation people outside the asset class sometimes assume.
At the larger, later-stage end, where companies have real revenue and a more active secondary market, valuation leans on the metrics of the business rather than on whatever the last round happened to price.
He does not accept that the asset class is broadly overvalued. “There are pockets which are hot and pockets where there is a lot of value.”
What settles it, on his reading, is not the carrying value but the cash. Exits and realised returns are the umpire, which is why he points advisers towards managers with a track record through more than one cycle and a demonstrated ability to return capitall, and why the allocation question is not whether to own this, but which layer a manager is buying, and at what price the last person paid.
Which is why the allocation question is not whether to own this, but which layer a manager is buying, and at what price the last person paid.
Laurence Parker-Brown is head of content at The Inside Network and managing editor of The Inside Adviser and Investor Strategy News.