Monday 9th November 2026
Why the last two years are the wrong guide for client portfolios
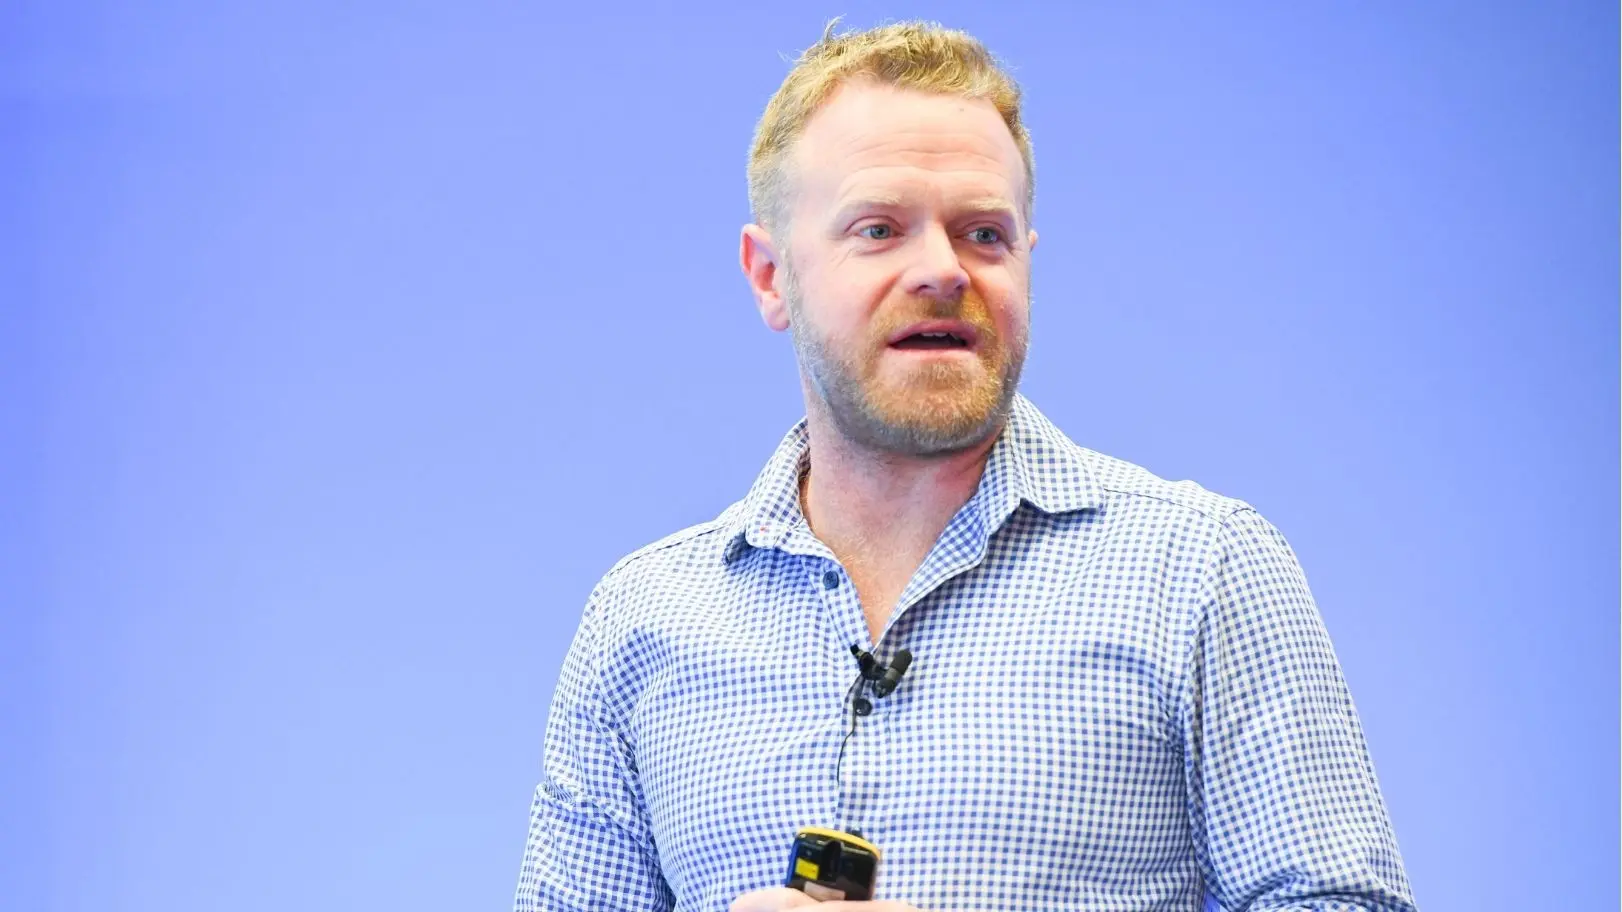
Genium Investment Partners’ Tim Murphy says only about one active manager in four beat its index last year because the index itself has narrowed to a handful of names, and that advisers who answer by chasing momentum are adding concentration to portfolios rather than removing it.
Roughly one active manager in four beat its index over the past year in US equity mutual funds according to Bloomberg Intelligence. Tim Murphy, co-chief executive and head of research at Genium Investment Partners, says Genium’s Australian peer groups tell much the same story.
The hit rate has been falling for three years. The global equity funds most widely held by private clients show the same trajectory. There are exceptions, but the median manager has struggled.
Murphy’s thesis is that the number says as much about the index as it does about the managers. Over the past 10 years the share of the index sitting in its 10 largest holdings has doubled in both the United States and emerging markets.
In the US, the weight of technology inside that top 10 now runs well beyond anything seen in 2000. Australia’s market is concentrated too, though in financials and resources, where the banks did an unusual amount of the work in outperformance for a period before that faded.
Three stocks, one market
Emerging markets is a great case study of this phenomenon. Until recently TSMC, Samsung and SK Hynix accounted between them for more than 30 per cent of the index, and Murphy notes that those three names drove almost all of the market’s return.
Managers who did not own a couple of them paid dearly. Over the 12 months to 30 June, several of the most widely used emerging markets strategies in Australia finished 20, 25 or 30 per cent or more behind the index.
The map also redrew itself inside a year. China and India, the subject of almost every emerging markets conversation for five years, saw their share of the index fall sharply while Taiwan and South Korea doubled.
“Has the world changed?” Murphy asks. “Have these traditional managers that focus on fundamentals lost the plot?”
One in four
His answer starts with the arithmetic of a market-cap weighted index. Random chance suggests half the stocks should beat it.
For three consecutive years, only about a quarter of US stocks have done so, and mostly the ones at the top. Over 30 years there is no precedent for that, and the nearest comparison is the run into the tech wreck. Nobody, he adds, has the bell to ring on when a correction arrives.
The gap has been worth real money. Three years in a broad emerging markets index returned about 60 per cent. The same three years in emerging markets technology returned about 150 per cent. Murphy says the question now landing in investment committees is whether the portfolio has that exposure, why not, and whether it should have more.
Momentum has been the factor doing the work. Murphy points to the Factor Olympics, published twice a year by research firm Finominal, which has had momentum at the top of the table for three years.
Part of the growth in quantitative and systematic investing he attributes to performance chasing, and part, in Australia, to regulation, with Your Future, Your Super pushing more institutional money towards benchmark-aware approaches.
“Momentum builds on itself and keeps driving itself, of course, until it does not.”
Two of the three strongest two-year runs for momentum on record are the past two years. The only stronger one immediately preceded the tech wreck. Murphy’s late-cycle markers are behavioural rather than valuation-based: assets in global levered and inverse equity ETFs have climbed steeply, and in Korea margin loans went through the roof over the past 12 months. Most forms of gambling are illegal there, he notes, so the equity market and its derivatives absorb money that would otherwise find them.
The cost of being early
Here is the part the concentration argument tends to skip. The case for holding the line rests on mean reversion, and mean reversion arrives without a date. Japan’s 1989 peak took more than three decades to reclaim.
A manager who avoided emerging markets technology on valuation grounds was right about the risk and roughly 90 percentage points behind over three years, and a client reading a statement does not see the distinction. The discipline is defensible across a cycle and expensive inside a year, and the client conversation happens annually.
Murphy’s answer is communication rather than repositioning. Be open with clients about why the results look as they do, and why the current settings are right for what comes next.
“Chasing short-term performance and momentum can work in the short term, but through a cycle it tends to end in misery,” he says.
Korean stock market performance in July has given advisers one early reading of what the end of it looks like. The work now is deciding which of the other concentrated markets delivers the next.
Laurence Parker-Brown is head of content at The Inside Network and managing editor of The Inside Adviser and Investor Strategy News.