

Thursday 22nd October 2026
Structure comes first: a fundamental shift in advice
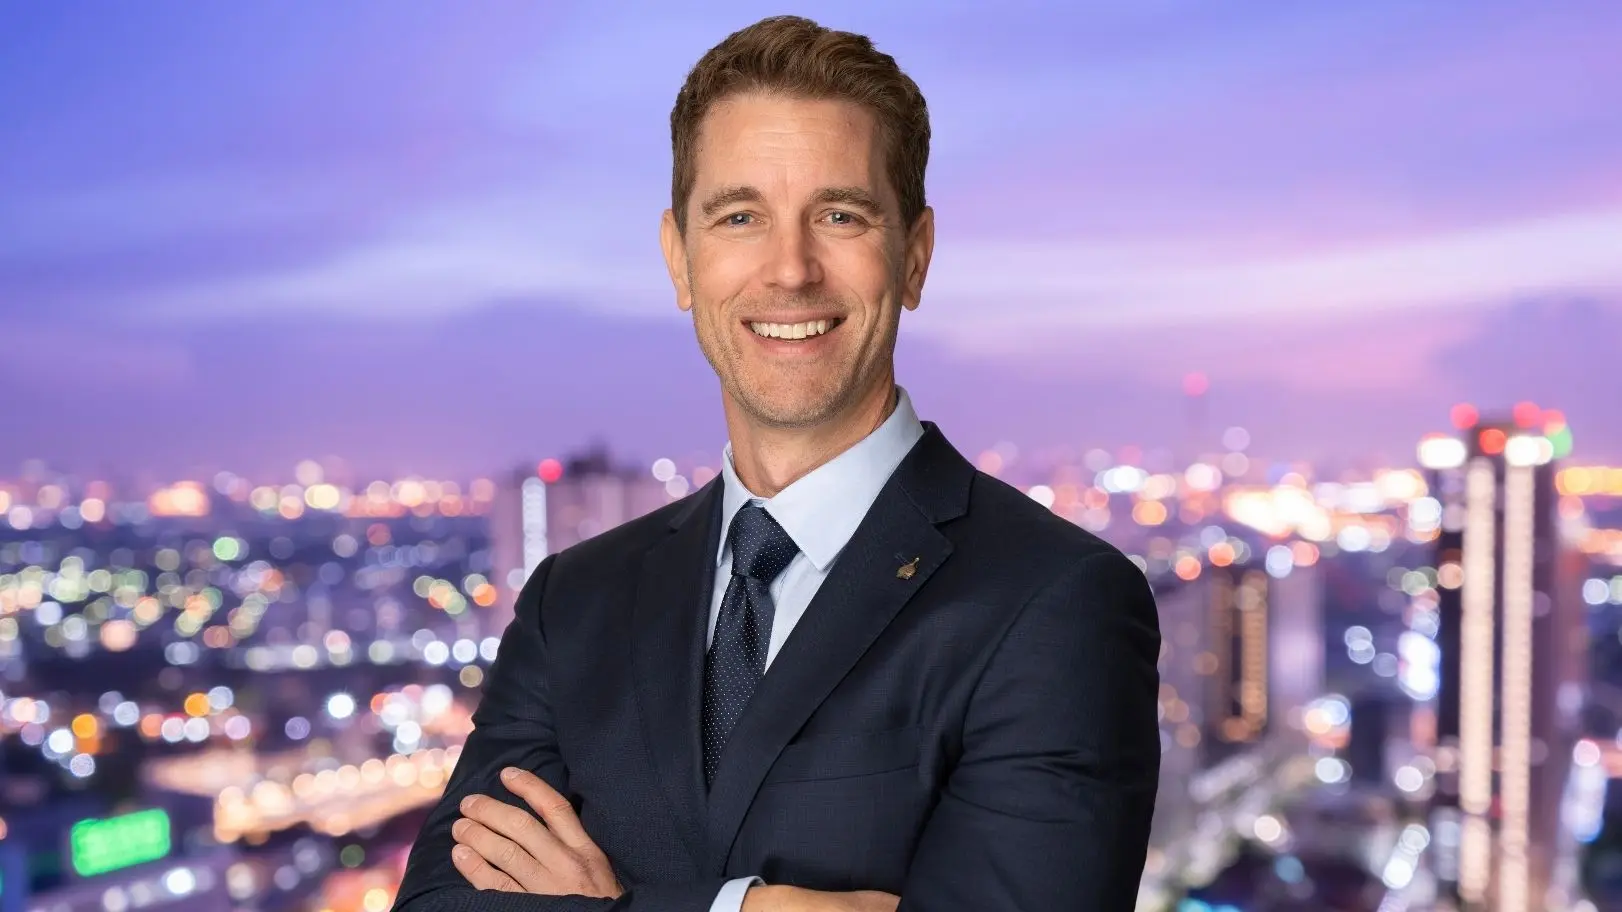
KeyInvest’s Jarrad Gray says grandparents increasingly ask how to vest money to grandchildren, and investment bonds answer with flexibility, control and tax-paid withdrawals after 10 years, outside the estate and running up to 99 years.
For years, Jarrad Gray has heard the same polite objection from advisers. Their client books lean towards retirees, with perhaps a small wedge of pre-retirees, and investment bonds seem built for somebody else.
“We can’t see the use case for a bond,” is how he recalls the typical response. Today, those same retirees arrive at their adviser’s office with a very different question.
“What’s a good way to vest some money to our grandchildren?”
As Senior Distribution Manager at KeyInvest, Gray works with advisers and family offices on investment solutions that prioritise flexibility, capital preservation and income certainty. He brings more than 25 years in financial services to the role, including time in the wealth management businesses of ANZ and CBA.
Across those years, he sees one question move to the centre of advice: where should wealth live once it grows beyond what super can hold? For many families, the answer now begins with the grandchildren.
Many of these grandparents have gained the most from rising property and market values. They often own homes they have held for decades, carry no debt and spend less than their pensions provide. Many also worry that their grandchildren will never afford a property of their own.
“I’d probably be wrong, but it feels like one in every five bonds that comes in is a grandparent who puts in $20,000, $30,000 or $50,000, then contributes every month to let it compound,” Gray says.
Some name the grandchild as a beneficiary, while others choose a vesting date. He describes the typical instruction in the client’s own words: “I’ll get this pot of money going, and they get it when they turn 21 as a birthday present. It will vest whether I’m alive or not.”
The structure behind those gifts has a long history. KeyInvest dates back to 1878, before Federation, and Gray explains that investment bonds descend from whole-of-life policies, which bundle life insurance with a savings plan.
When the insurance and investment components separate, bonds keep the investment side but stay under the Life Act. “A halfway house between the two,” he says.
That old structure now finds itself back in demand. Gray believes the reasons reveal a great deal about how clients think about wealth.
Why clients want more than one pot
Gray traces the change to steady policy reform, both inside and outside super. He jokes that super once seemed to have as many rule changes as days since its introduction. Each change chips away at the confidence clients once placed in super as their single retirement pot.
Younger clients, he notes, view super very differently from baby boomers. Many boomers saw it as their main source of retirement wealth after the family home.
“Clients now think of super and non-super together as the way to approach their goals and how they grow wealth over time,” he says.
He groups what clients want into three needs. The first is access, because life rarely waits for preservation age. “People want to access their capital when their life circumstances change, and they don’t want to wait for a condition of release.”
The second is control and protection, which he says “go hand in glove” as families grow more complex. The third is tax and timing. Clients want to manage tax outcomes across different time horizons, without a heavy penalty when they need to move capital.
Where super ends and bonds begin
“Each structure has a job to do,” Gray says, and he uses a heat map to explain it. For years, the hot spots in most advice files clustered around trusts and super. He gives super its due.
“It still remains one of the more tax-effective structures to invest in. But it has a lot of limitations, and we’ve seen those bite more over time.”
Contribution caps and taxes aimed at larger balances, he explains, put a collar on flexibility, access and control. Advisers now move the heat map around according to each client’s goals.
Investment bonds earn their place on that map through the way they work. Gray asks advisers to picture “an investment company you can take off the shelf that’s ready to go, with an investment menu underneath it.”
The bond pays tax internally, capped at the 30 per cent company rate. Investors can switch between options inside it without triggering capital gains tax. They can also add up to 125 per cent of the previous year’s contribution. After 10 years, withdrawals come out tax-paid in the investor’s hands.
The estate planning features stand out. A bond can pass to a nominated beneficiary outside the estate, or vest to a child at a future date, without tax consequences. Super can do something similar. However, Gray points to the tax on death benefits paid to non-dependants, which catches many families out.
“Structure is now part of the investment decision. We talk a lot now about asset location rather than asset allocation.”
What a bond can and cannot do
Gray takes care to explain where investment bonds fall short, starting with a common misconception about tax. Some clients expect a bond to trim this year’s tax bill, and he is quick to correct that expectation.
“An investment into a bond is not a tax-deductible event, so investing by itself doesn’t reduce your tax liability.” Instead, the advantage builds gradually as the years pass.
A bond tends to suit an investor on a marginal rate above 30 per cent, because it lets them hold investments inside a structure with a lower effective rate.
Clients who contribute regularly also get the most from the contribution rules, which reward a steady approach. An investor who skips a year can still add money later, but doing so restarts the 10-year clock. Gray’s guidance on this point is simple: “make sure you’re getting advice and understand that you will restart the 10-year tax-paid period.”
For clients who want to add a lump sum after a break, he suggests a practical alternative. They can leave the original bond rolling towards its tax-paid status and open a fresh bond for the new money.
He also credits policy, more than the product, for the renewed interest. “Strategically, there has always been an undercurrent of savvy advisers using the particular features and benefits of bonds,” he says.
Ongoing changes to tax and super policy have revived interest in structures of every kind. Gray counts bonds as one option among many: “we’re just one of those.”
Fair, equal and outside the estate
Family wealth brings its own complications. Household wealth has grown strongly across property and markets, and families have become more complex. Gray sees estate disputes rising alongside estate values.
“If an estate is valued at more than $3 million, it gets contested something like 75 per cent of the time, and of those, three-quarters end up in favour of those seeking a judgment from the estate.”
Bonds give advisers one way to respond. For blended families and second relationships, Gray calls the bond “a very powerful way to direct wealth to the people you want it to go to, outside the estate.”
Business owners can use one to quarantine funds away from business risk. Rural and business families with large, illiquid assets can use bonds to support estate equalisation for children who step away from the farm or the business.
“That has been a struggle for advisers to manage, and they haven’t always had the best tools,” he says.
For Gray, the structure comes first, and the allocation follows. He describes structure as “the filter through which decisions are made more and more often.” Bonds can run for 99 years, and some families use them, he says, “as a pot of money that continues in perpetuity, a house, if you like, for family wealth.”
For grandparents who worry their grandchildren may never afford a home of their own, that image carries extra weight. The money they set aside for a 21st birthday may become the foundation of that house.
Cristina is a contributor and content manager at The Inside Network.