Monday 12th October 2026
Performance fees are becoming a ratings conviction factor
Zenith has upgraded the ClearBridge Select Opportunities Fund to highly recommended after five years at recommended. The trigger was not performance. Here is what the equity fund ratings decision reveals about how research houses now weigh fees.
A fund that moves up a ratings tier has usually just had a strong run, and this one moved for a different reason. Zenith Investment Partners upgraded the ClearBridge Select Opportunities Fund after ClearBridge removed the performance fee, and the research house put that change at the centre of its reasoning.
Zenith says its conviction in the fund “has strengthened following the enhancement to its fee structure”, which it expects will lead to improved investment outcomes. The research house adds that it holds “the fund’s portfolio manager and long-standing investment process in high regard”, bringing continuity into the assessment alongside the fee.
The fee change
ClearBridge removed the performance fee on the fund in 2025, and the sequence is worth noting for advisers assessing active Australian equity funds that still carry one. The fee change came first, and the ratings upgrade followed.
A performance fee takes a share of returns above a hurdle, so the client keeps less of the upside in the years a strategy works hardest. Removing one lifts the net result in those years and makes the fee line easier to model across a client portfolio, which is the practical argument behind the change.
Research houses increasingly treat fee design as a factor in its own right rather than as an input to net-of-fees return calculations.
The track record
ClearBridge Investments’ Australian Equities team manages the fund, running a high-conviction strategy that targets mispriced ASX-listed stocks.
Franklin Templeton, the fund’s responsible entity, reports returns of 16.91 per cent over one year, 9.42 per cent a year over five years and 10.40 per cent a year over 10 years, at 30 June 2026. The S&P/ASX 200 Accumulation Index returned 6.11, 7.76 and 9.45 per cent over the same periods. The manager says the fund ranked in the first quartile of its sector over one, two, three and five years.
Outperformance that holds across one, five and 10-year periods is the pattern research houses look for, because it points to process rather than to a single favourable stretch.
Advisers reviewing the fund for client portfolios will want the full Zenith Product Assessment alongside the headline figures, since the report sets out drawdown behaviour and return attribution in a way summary numbers cannot.
Team continuity
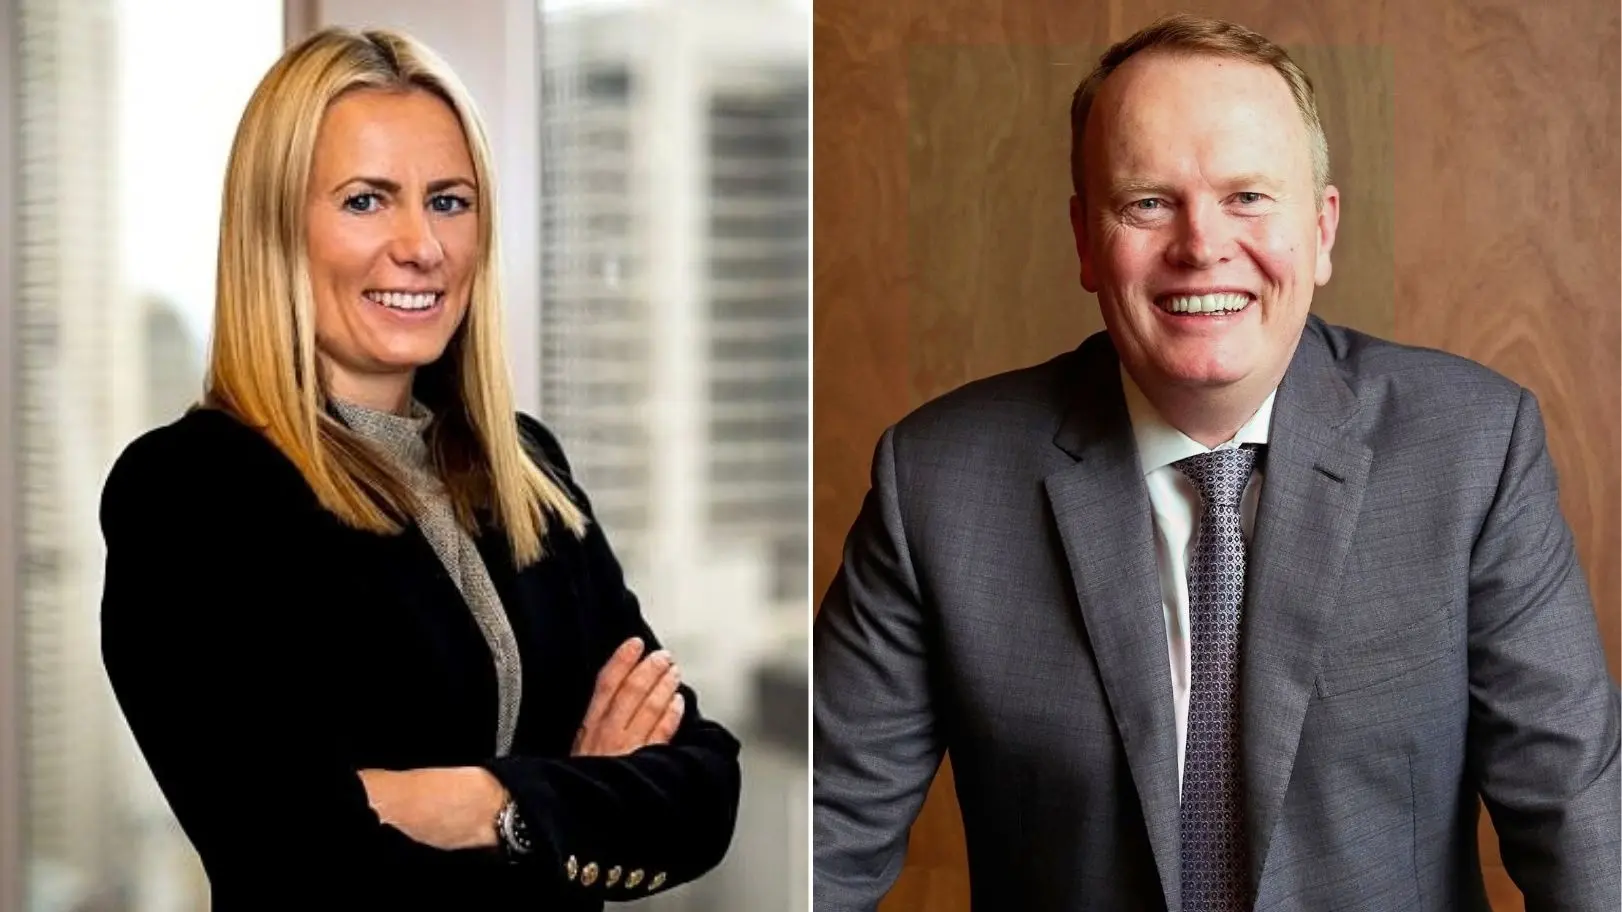
Team stability is the other factor Zenith weighed. Reece Birtles, managing director, portfolio manager and head of Australian equities at ClearBridge, co-manages the strategy with Michael Slack, managing director, portfolio manager and director of research. Birtles has more than three decades in the industry, almost all of it with this team.
Zenith describes the broader investment team as collegiate, with rigorous internal debate, and rates it as experienced and adequately resourced. Co-management by two long-tenured portfolio managers answers the key person question advisers raise whenever a strategy depends on one individual.
Birtles describes a process that is fundamentally driven and forward-looking.
“We look for the most compelling undervalued stock ideas on a forward-looking basis, and we let that valuation bias play out through the cycle.”
There is of course a counter argument to that logic. A fund with a clear valuation bias will meet stretches where the market pays for growth rather than for value, and Australian value managers spent much of the period from 2015 to 2020 in exactly that position.
The returns across one, five and 10 years suggest this approach has carried through those conditions, though it remains a deliberate style allocation rather than a core holding.
The second rating
Zenith also credits the analyst bench behind the portfolio managers, saying it is “encouraged by its strong connection with the stock research performed by the analysts”. That shapes how advisers read a high-conviction fund, because the rating rests on the research process rather than on individual calls.
Felicity Walsh, managing director of Franklin Templeton Australia, links the upgrade to both the fee change and the team’s record.
“We removed the performance fee on this fund last year to better align outcomes for investors, and it is pleasing to see that change recognised by Zenith alongside the fund’s investment performance,” she says.
The fund also holds a recommended rating from Lonsec, published in October 2025. Advisers who use both research houses will note that review cycles run independently.
Fee pressure across active Australian equities is not easing, and this is a working example of how a research house weighs it. Advisers watching the category now have a reference point for what a fee restructure is worth when a fund next comes up for review.
Cristina is a contributor and content manager at The Inside Network.