Monday 28th September 2026
Genium and MST agree to share research, and approved lists will feel it
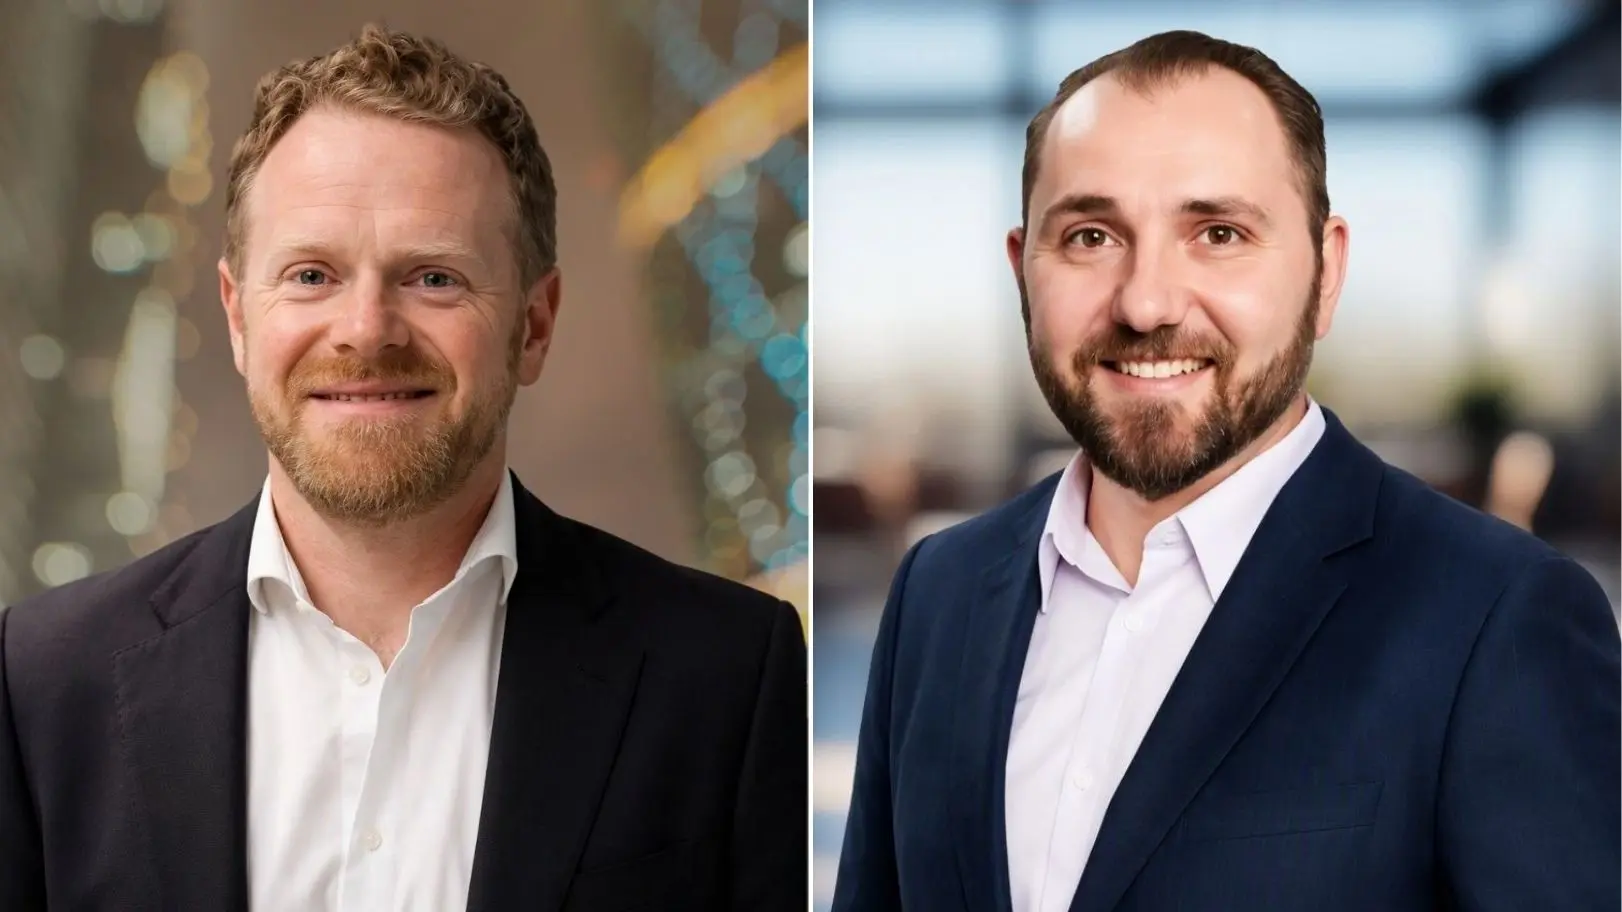
Genium and MST Investment Solutions share research rather than merge operations, an arrangement that gives advisers broader coverage while raising a question about where each opinion originates.
Most advisers can name the platform they use and the model portfolios they run for clients, yet far fewer could describe the investment research chain that produced the approved list underneath. That chain has shifted for two providers, and the shift is worth understanding even for practices that never see a ratings report from either firm.
Genium Investment Partners and MST Investment Solutions have entered a research partnership. MST Investment Solutions draws on Genium’s investment manager research and ratings across the major asset classes, along with its analytics and reporting.
Genium reads MST Financial’s proprietary Australian equity research, which the broker built for the wealth adviser market rather than for institutional trading desks.
Neither firm is merging anything. The arrangement operates at the research layer alone. Both continue to run their own investment processes, and each keeps full responsibility for manager selection, portfolio construction, asset allocation and client relationships. Advisers and licensees deal with whoever they dealt with before.
Why investment research keeps moving out of the practice
The commercial logic here follows a decade-long shift in how advice businesses buy investment expertise. Practices that once maintained their own investment committee and their own product research now buy both, and the managed account structure has become the vehicle that carries the decision.
The scale of the shift shows up in the numbers. Managed accounts held $292.9 billion at 31 December 2025, on the IMAP and Milliman census, after net inflows of $21.7 billion over the six months and annual growth of 25.8 per cent. Money moves that quickly only when the underlying pressures are structural.
Compliance obligations have risen, fee pressure has compressed the margin available for in-house analysis, and clients increasingly expect a documented answer to the question of how a portfolio decision was reached.
Genium and MST both position themselves against that backdrop. Genium describes itself as a full-service research ratings, asset consulting and investment management firm, founded in 2013 and moving into research ratings in 2024.
Tim Murphy, co-chief executive and head of research at Genium, joined the firm in 2023 after nearly two decades at Morningstar, where he ran manager research across Asia Pacific. MST Investment Solutions is newer still, launched in February 2026 as the equity research and portfolio advisory arm of MST Financial.
Damian Cilmi, head of investment solutions at MST Financial, arrived from Praemium to lead it.
“Advice businesses are increasingly looking to work with external domain experts to improve client outcomes and their own performance.”
Self-selection shapes the coverage list
One line from Murphy deserves more attention than a partnership announcement usually gets. Explaining what MST receives, he described “Genium’s research reports on funds we self-select into the ratings process”.
The phrase describes how most retail research coverage works in Australia. A ratings house does not analyse every fund in a category and publish a ranked field. Funds enter the ratings process by selection, and what a report covers is settled before any analysis begins.
Which party makes that selection differs between houses, and a ratings report rarely says. That is the question worth putting to a provider, because the answer draws the boundary around everything the rating can support.
Two practical consequences follow for an adviser reading a ratings report. The absence of a rating says nothing about a strategy’s quality, only that it never entered the process.
And a top rating means the strategy stood above the funds that entered, not above every option available to a client. Advisers who treat a covered universe as the whole market inherit a narrower opportunity set than they realise, and their file notes will show it.
Where shared research narrows the field
The balancing point comes from the same arrangement that makes the deal useful. Practices often hold two investment research relationships precisely to get a second reading on a manager, and that second reading loses value as the underlying analysis converges.
If two providers work from the same manager reports, an adviser who checks one view against the other may be reading one view twice.
Australian advisers have a genuine stake in this. A rating carries weight in a governance file because it represents an opinion formed away from the other opinions in that file.
Pooling inputs reduces the number of separate lines of sight even while the number of provider relationships stays the same, and fewer independent readings mean fewer moments where an analyst dissents early on a strategy the rest of the market likes.
Genium’s response rests partly on its ownership structure. The firm is Australian-owned and principal-led, which it contrasts with a market dominated by globally owned and listed competitors.
That independence is real at the ownership level. It says nothing, on its own, about how many separate opinions an adviser is buying when two providers share a research pool.
The question for the next investment committee
Advisers do not need to change anything because of this arrangement. They do need a clear answer to a question that applies to every research relationship they hold. Where does this opinion originate, and whose work does it duplicate?
A provider can say which reports come from its own analysts, which arrive through a partner, and how the ratings process decides what gets covered at all. The answers belong in the investment governance file regardless.
As more of the research layer consolidates through arrangements like this one, those answers become the record of how carefully a practice chose the people thinking on its behalf.
Cristina is a contributor and content manager at The Inside Network.