Thursday 5th November 2026
CPA Australia wants every trust rule on the table before the EET election
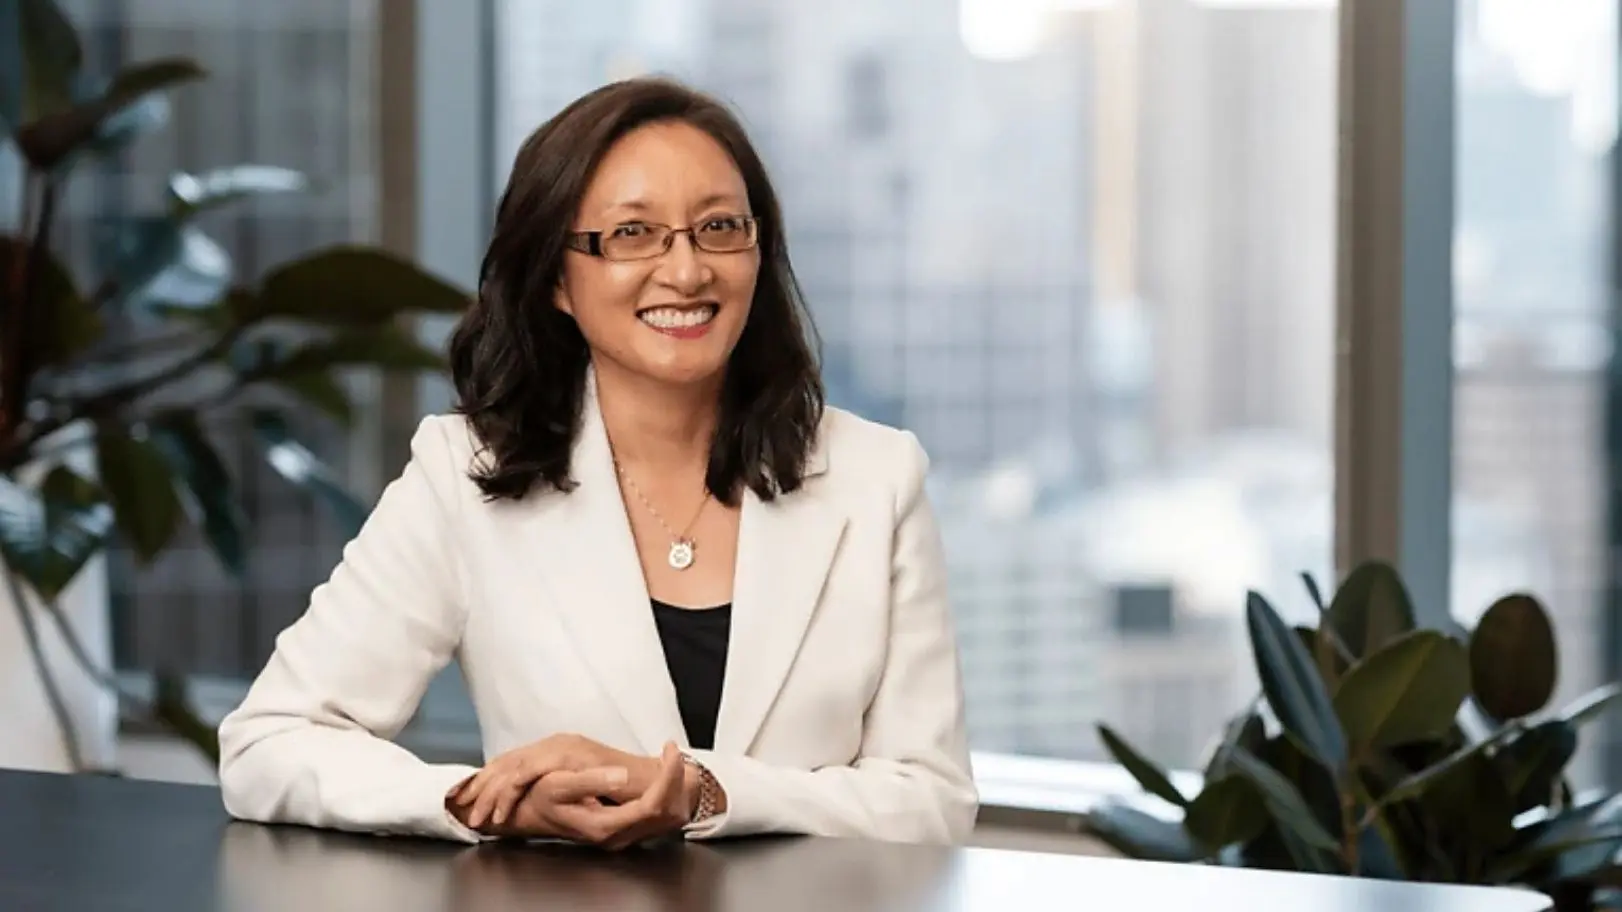
CPA Australia’s Jenny Wong urges the Senate to make discretionary trust reforms complete and workable before families choose, citing 12 unreleased legislative instruments, a single election year and compliance costs far above Treasury’s estimate.
CPA Australia urges the Senate to make sure the Government’s discretionary trust reforms are complete and workable before families and small businesses face decisions they cannot reverse. The professional body sets out its case in a submission to the Senate Economics Legislation Committee inquiry into the minimum tax on discretionary trusts.
The submission, lodged ahead of the committee’s public hearings, recognises that the legislation has improved significantly following consultation. CPA Australia’s concern is that key parts of the regime remain unfinished, and its tax lead, Jenny Wong, is clear about where the organisation stands.
“CPA Australia is not opposing trust reform,” Wong says. “But families are being asked to make permanent decisions before the Government has finished writing the rules.”
For advisers, the reforms reach into some of the most common structures in client files. Many business owners and family groups hold investments, business interests and property through discretionary trusts. That makes the timing of the decisions ahead an important part of advice conversations, well before the new rules take effect.
Advisers and accountants who work with these clients can expect questions about restructuring, the roll-over window and the election each trust must make.
The fine print
The Bills give the Minister 12 powers to make legislative instruments. In its submission dated 28 October 2026, CPA Australia notes that the Government has released none of them, even in draft.
The key dates, by contrast, are already set. The roll-over window for restructuring opens on 1 July 2027, and existing trusts have a single income year, 2028–29, to make a permanent excluded election trust (EET) election.
Wong puts the concern in everyday terms.
“No Australian would sign a contract before seeing the full terms and conditions. Tax reform should be no different.”
Counting the cost
CPA Australia estimates that the professional advice needed to respond to the trust reforms will cost $2.0 billion to $2.8 billion. That figure comes before any restructuring, implementation or state duty costs. The organisation also puts ongoing compliance costs at $221 million to $595 million a year, compared with Treasury’s estimate of $48 million.
According to CPA Australia, the two estimates are broadly similar on workload. The difference comes down to pricing. Treasury values an hour of advice at $91.54, while families will generally pay commercial professional rates.
The same families, businesses and advisers are also preparing for the Government’s capital gains tax reforms, payday super and other regulatory changes. Taken together, CPA Australia estimates the trust and capital gains tax measures could add $516 million to $1.137 billion a year in ongoing compliance costs.
Wong is careful to acknowledge the longer-term thinking behind the reforms.
“We acknowledge the Government’s expectation that, over time, more businesses will choose simpler structures, including companies, rather than discretionary trusts. A simpler tax system can improve productivity. But those gains lie in the future, while the transition costs fall on today’s families and small businesses.”
A practical path
CPA Australia’s view is that targeted, practical amendments can improve the legislation without undermining the Government’s policy objectives. It asks the committee to prioritise three recommendations.
The first is to release all ministerial determinations and outstanding implementation rules before taxpayers must make irreversible choices. The second is to make the EET election workable, with practical ways to correct honest mistakes and handle ordinary family events. The third is to publish updated compliance cost estimates once the rules are final, and to legislate an independent review within three years.
For advisers working alongside accountants on trust structures, the second recommendation carries particular weight. A permanent election that allows for honest mistakes and the ordinary changes in family life would give clients greater confidence when they make their choice.
Wong sees the recommendations as a way to help the reform deliver on its promise. “Good policy can become bad policy if implementation is rushed,” she says.
“This reform should leave the tax system simpler as well as fairer. If these rules come in, the rules they replace should go.”
Cristina is a contributor and content manager at The Inside Network.