Monday 9th November 2026
Half the private credit funds in ASIC’s review had no written policy for default
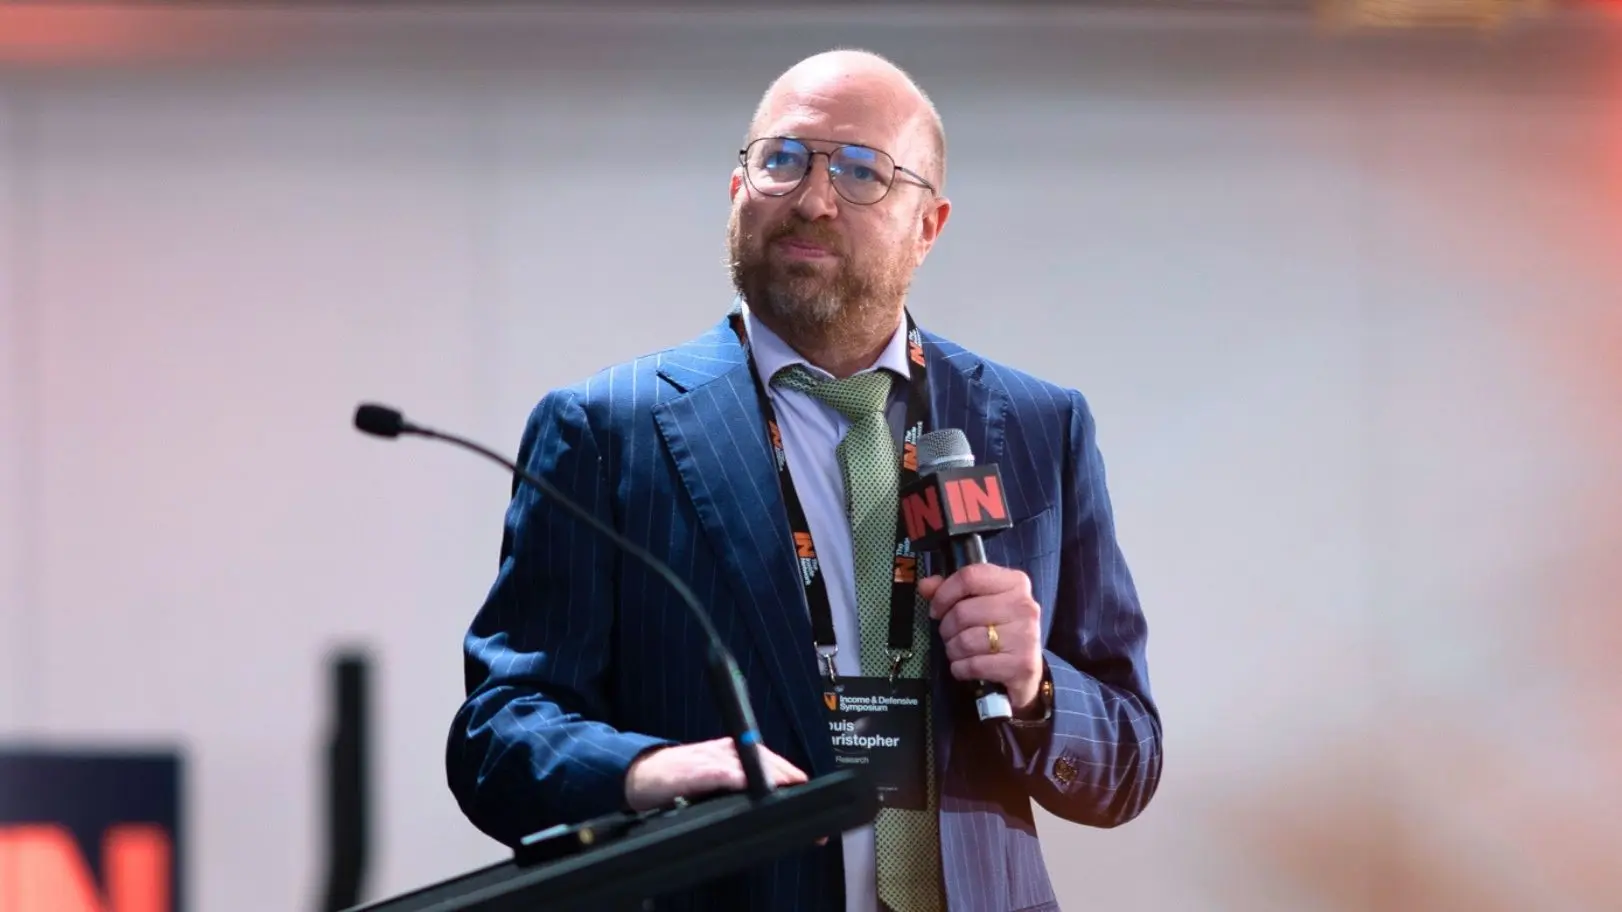
SQM Research’s Louis Christopher says roughly half the 52 funds covered by ASIC’s private credit review lacked written policies for provisioning, impairment and default.
Australian private credit is facing its first public reappraisal, and the temptation is to read the headlines as a verdict on the asset class. Louis Christopher, managing director at SQM Research, has been reviewing these funds since 2007, when they went by the name mortgage trusts and the problems were loan caveats and a run on liquidity.
“We’re going to get through the current storm that’s there, and it’s definitely a storm. And the sector will evolve,” Christopher says.
What has been exposed is less the lending than the reporting around it. Christopher puts the sector at roughly $213 billion on ASIC’s numbers, from a review covering 52 funds, and says about half of those funds did not have written policies for provisioning, impairment and default. Everything that follows from that is a disclosure problem rather than a credit one.
Definitions
The first issue is that the vocabulary is not standardised, which makes fund-to-fund comparison close to meaningless. “Arrears are about a definition and not just a number,” Christopher says.
One manager counts a loan as in arrears at a day past due, another at 30 days, another at 90, and whether an arrear has become a default is a separate judgment again. The same looseness applies further along. A developer runs into trouble and its loan receives an extension. The loan can then reappear in reporting as a new loan, which removes it from the arrears figure without changing anything about the borrower.
The loan-to-value ratio
Loan-to-value ratios carry the same problem. Christopher’s point is that they are only as good as their basis and their vintage. A valuation struck as-is describes the site today. One struck at completion describes a building that may not yet exist. That is appropriate on a project already under construction and considerably less so on vacant land.
Beyond that sits a further question about the ratio: do funds measure it against the drawn balance or the facility limit? Another is whether the valuation includes or excludes GST.
A portfolio average of 65 per cent can contain two substantial loans written at more than 80 per cent. That is why he asks for the distribution by band rather than the mean. The same logic applies to distributions. Part of a book can stop paying while the fund’s distribution holds steady because the manager would rather not explain a cut.
ASIC’s position is that genuine asset cash flow should support a distribution. Christopher’s own test is the cash interest received against the interest paid out.
“Governance failures precede credit failures.”
The moving document
One example he offers is a manager who, days after receiving a draft research report, issued a new information memorandum. The revised document allowed the fund to invest entirely in one state, relaxed its borrower concentration limits, changed its default parameters and permitted gearing.
An information memorandum is easier to change than a product disclosure statement, which makes the version history worth asking for. Christopher has no objection to a manager tightening its rules, and every objection to one loosening them while a problem is developing.
The Bathla receivership has made the concentration argument for him. The group carried around $3 billion of debt across some 520 separate subsidiary entities. More than a dozen non-bank lenders are named so far. Those entity names are the practical difficulty. A manager’s exposure to one sponsor is not visible on a look-through basis and has to be aggregated and verified deliberately.
Christopher has seen books with around a quarter of their assets exposed to the one group. He has also seen managers who increased exposure to Bathla in an attempt to trade out of the position.
Where the risk builds
Land loans should repay their investors, though slowly. Loans against projects near completion should be reasonably well placed, since those properties have to sell. The difficulty sits in the middle, with part-built projects that now need a new builder, and a new builder will want changes that cost money the lender has to fund.
That is where the optimism needs qualifying. Exactly that sequence squeezes an LVR that looked comfortable at origination. The extra funding comes against a valuation that has to hold through a completion and then a sale into a housing downturn.
Getting the money back and getting the expected return are different propositions, and the gap between them shows up as time rather than as a loss, until it does not. Christopher expects some funds to narrow distributions and one or two to remove them entirely.
He also cautions against assuming the sector is as diversified as it appears, since a credit event of sufficient size travels across managers even when their loan books look distinct. “The gap between well-run and poorly run managers will be priced and rated, rather than assumed away by uniform headline yields,” Christopher says.
Laurence Parker-Brown is head of content at The Inside Network and managing editor of The Inside Adviser and Investor Strategy News.