Saturday 7th November 2026
The ‘air pocket’ in small caps and the stocks set to close it
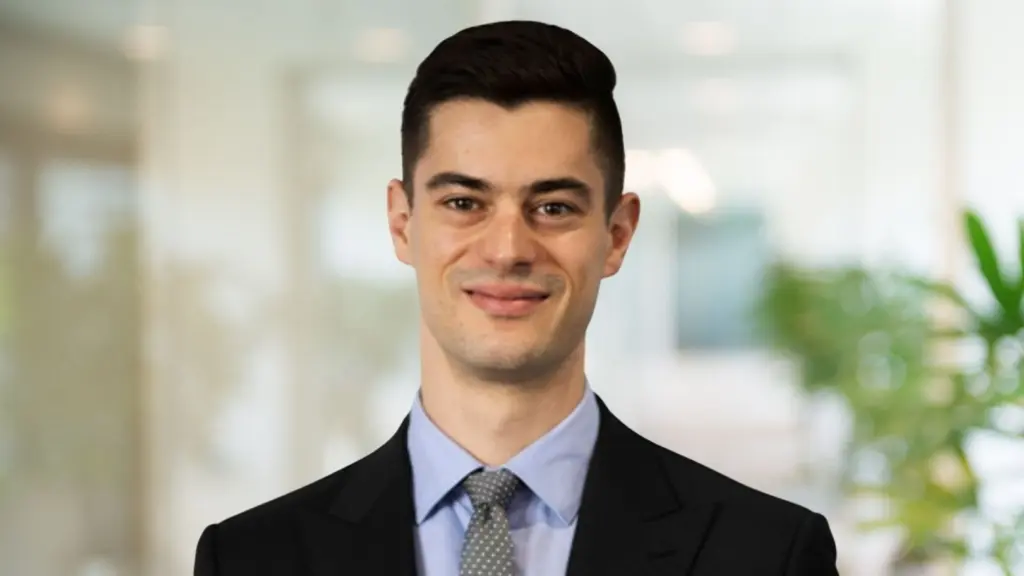
Ellerston Capital’s Jack Briggs says low starting valuations leave Australian small caps priced to reward earnings beats, finding opportunities in South East Queensland infrastructure, housing undersupply and a recovering software sector.
When investors price in further rate rises and a weakening property market, they tend to sell smaller companies first and ask questions later. Jack Briggs, portfolio manager of the Ellerston Capital Emerging Leaders Fund, treats that selling as the starting point for opportunity, because it leaves many Australian small and micro caps trading well below their fundamental value.
The premise has since been tested, with the Reserve Bank lifting the cash rate to 4.85 per cent on 3 November 2026, its fifth increase of the year and an 18-year high, in a tightening cycle that began in November 2025.
In Briggs’s view, a low starting valuation changes how the market responds to good news. When a company surprises on earnings, analysts revise their forecasts, and the share price has a long way to travel before it reflects what the business is worth.
“When these companies deliver outsized earnings performance, leading to revisions in the market’s expectations of their future cash flows, there is strong share price performance. There’s almost an ‘air pocket’ they need to catch back up to, to align the price with fundamental value,” Briggs explains.
Building in the north
Briggs identifies South East Queensland as one of the strongest parts of a mixed domestic economy. Strong net migration places pressure on the region’s infrastructure, and after years of spending less than New South Wales and Victoria, the Queensland government is catching up. Total infrastructure spending in the state is set to rise from $10 billion in FY25 to $30 billion in FY30, a 200 per cent increase over five years.
The Brisbane Olympics draw most of the attention, but Briggs looks past the headline event to the pipeline behind it.
“Crucially, that’s a diversified pipeline of projects across a range of different infrastructure types. It’s not dependent on one big project. The Olympics is a key call out, being a single one off that’s going to pop into that pipeline and generate some tension through the value chain, but it is just a component of that,” he says.
The Wagners case
Wagners, the family-founded cement and concrete business, shows how that spending flows through to earnings. Briggs describes the company as part of the region’s concrete oligopoly and notes that it is vertically integrated.
For years its quarries, processing plants and batch plants ran well below their fixed capacity, which weighed on the share price. That capacity is now tight, and the fixed cost base works in the company’s favour.
“What happens when you have a big cyclical uplift through a fixed-cost and fixed-distribution network is you get three things all at once that drive earnings, strong volume, strong price and strong margins,” Briggs observes.
Wagners lifted earnings 41 per cent in FY26, and Briggs expects growth of 20 per cent or more across the following couple of years. Its composite fibre power pole business doubled its earnings in FY26 and looks set for another strong year in FY27 as production capacity expands.
Housing undersupply
The housing numbers have worsened considerably since Briggs set out his case in early October. National home prices had then fallen 3.7 per cent over three months, with early spring auction volumes down 30 per cent on the prior year. Prices have now fallen for seven consecutive months at the steepest pace in four decades, and CommBank economists are forecasting a record 14 per cent peak-to-trough decline.
Listed real estate stocks had already dropped 20 per cent since the tightening cycle began, including 10 per cent in August alone. Briggs argues that weakness overlooks a longer-term force working in the sector’s favour.
“We think investors are missing in that broader decline in real estate share prices is that there is a structural undersupply of housing in Australia. It’s broad based, and it’s particularly pronounced in WA and Queensland, which are experiencing the strongest population growth,” he notes.
A deeper price downturn does not resolve that shortfall, and it tends to suppress new building, which widens the shortage Briggs is pointing at.
His chosen exposure reflects that reading. He highlights Eureka Group, a long-term rental provider delivering sustained rental growth of 5 to 7 per cent a year while expanding its footprint of villages at attractive acquisition prices. Rental income carries far less exposure to falling dwelling prices than a developer’s margin.
Software in focus
Software stocks show how quickly sentiment can turn. From a peak around October 2025, fears that AI tools could disrupt software business models drove a fall of about 40 per cent in software indices before they bottomed in March and April 2026. US software indices had recovered to near their previous highs by early October as earnings came through.
The Australian tech index has barely moved off its April low, and Briggs attributes that to weak earnings. Only five local companies recorded positive revisions to two-year forward EBIT across 2026 to that point.
Bravura Solutions is one of the five and the fund’s biggest contributor. Under new management, the wealth administration software provider has moved from loss-making to sector-leading profit margins of 30 per cent. It upgraded cash earnings by 76 per cent over FY26, delivered 15 per cent organic revenue growth, and its share price rose from $2 to just over $3.
“The market still thinks this is a boring, mature turnaround story.”
The company’s own actions suggest otherwise, with its FY26 result on 12 August 2026 carrying a $63.1 million profit turnaround, a A$50 million buyback and an AIM listing. Briggs expects double-digit growth again in FY27, well ahead of the low single-digit growth the market is positioned for.
Testing the thesis
There is of course a counter argument to this approach. Smaller companies tend to feel higher rates and slower consumer demand more sharply than their larger peers, and a cheap starting valuation offers little support if earnings fall short.
Briggs answers through selectivity, favouring businesses with their own growth drivers, whether that is a state infrastructure pipeline, a housing shortage or a turnaround the market has yet to price. He looks for niches carrying high growth, or where a young disruptive newcomer is taking share from incumbents, and reads the economy as holding enough good patches to support that approach.
For Briggs, the broader macroeconomic mood creates the mispricing, and company earnings correct it.
“A number of businesses have been unfairly punished by the broader macroeconomic backdrop, but with a little bit of positivity will flip back to their intrinsic value,” he adds.
For advisers building exposure to Australian small caps and micro caps into client portfolios, the opportunity rests on earnings delivery. Briggs sees a market that underprices that delivery as fertile ground for disciplined stock pickers.
Cristina is a contributor and content manager at The Inside Network.