Thursday 17th September 2026
Australian equity funds just had their second-worst half against the index
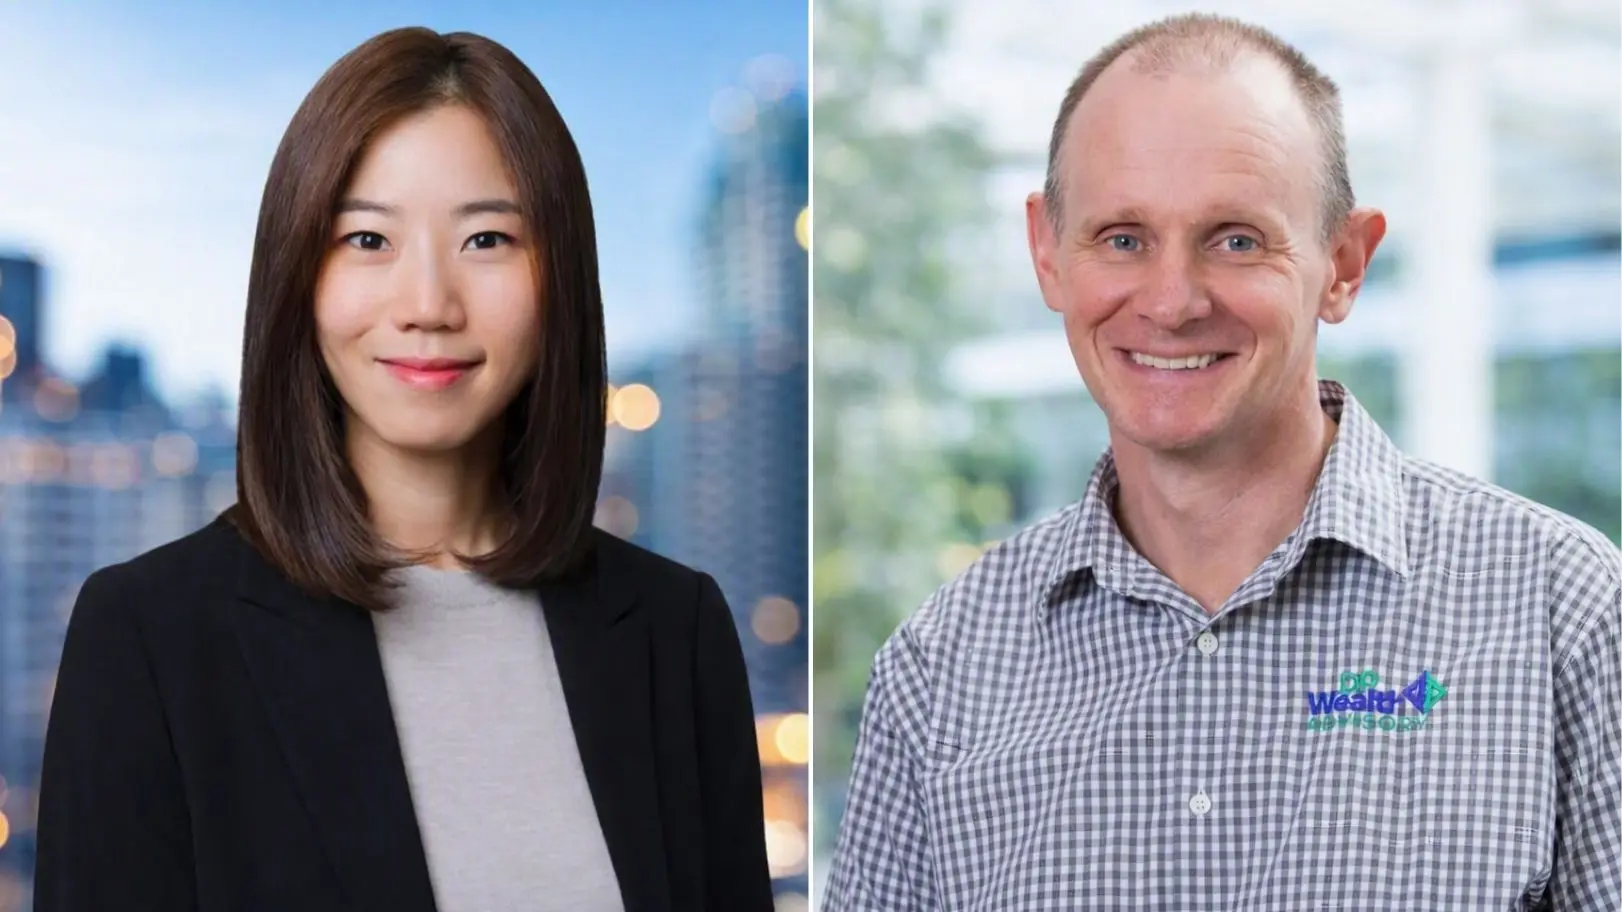
Sue Lee's mid-year SPIVA scorecard shows three in four Australian equity funds trailing the ASX 200, the weakest result since 2013, while adviser Andrew Wielandt says the data guides which active fees are worth paying.
Three in four Australian general equity funds trailed the S&P/ASX 200 in last year’s SPIVA scorecard. The mid-year 2026 update, released by S&P Dow Jones Indices this month, shows the story has not moved on. It has hardened.
Sue Lee, APAC head of index investment strategy at S&P Dow Jones Indices, says the first half produced the second-worst result for Australian equity managers since the firm began the study in 2013. Seventy-eight per cent of active funds failed to beat the benchmark, as the S&P/ASX 200 gained 2.4 per cent while the average active manager returned just 0.4 per cent on an asset-weighted basis. Four of the five categories S&P DJI tracks posted majority underperformance.
“Still, after the fees, active funds are having a hard time to beat the benchmark,” Lee says. “For Australian domestic equity funds, the headwinds actually seem to be much bigger.”
The concentration problem
Concentration is doing a lot of the work. The top 20 stocks on the ASX now make up about 64 per cent of the index, and Australian mandates tend to be run close to benchmark. Getting a handful of smaller calls right barely moves the outcome if the largest names, which carry most of the index weight, are misjudged.
“Even if you make right calls in small names, if your call is not right among these top 20 stocks, it’s actually quite hard,” Lee says. She points to a steady decline in the number of Australian large-cap active funds still operating, once the most crowded category in the local market.
A-REITs tell a similar story with one added twist. Goodman Group now accounts for close to 40 per cent of the Australian A-REIT index, so the category’s headline result in any period turns largely on how funds are positioned against a single stock. Goodman underperformed in the first half, and funds that underweighted it were likely the ones that came out ahead.
The bonds exception, and the persistence problem
Fixed income remains the outlier. It is the only category where a slim majority of active funds still beat their benchmark, and Lee says that has historically held for some other bond markets, not just in Australia.
Active managers have leaned on corporate credit for extra yield over government bonds and captured capital gains as spreads tightened in recent years. That tailwind is fading. Credit spreads are now near their most compressed levels on record, and the underperformance rate in Australian bonds funds rose to 44 per cent, up from 27 per cent in the 2025 scorecard.
“You have to do some math and look at the trade-off,” Lee says. “Fixed income is the area where the fee matters more than equities, because the absolute return you can get from bonds is usually much smaller.”
Why past winners don’t last
The scorecard’s persistence data is arguably the harder finding for anyone using past performance to select a manager.
Of the funds that ranked in the top quartile for the five years to December 2020, only 22 per cent held that ranking in the following period, and 47 per cent fell to the bottom quartile or merged/liquidated altogether.
Liquidation rates climb the longer the horizon too, from 3 per cent over the first half of 2026 to 40 per cent over ten years and more than half over fifteen.
“Finding the outperformers in advance is a real challenge. We’re just looking at all the data from hindsight. In reality we have the extra challenge of finding them in advance.”
None of this makes the case for abandoning active management outright. Lee points to categories, among them Australian small- and mid-cap equities and parts of fixed income, where a slim majority of managers have added value, can still earn a fee. The scorecard is a record of what happened, not a guarantee of what happens next.
That is how advisers reading the scorecard tend to use it too. Andrew Wielandt, director at DP Wealth Advisory, treats the data as a guide to where a client is better off paying for an active manager and where they are not.
“To me, SPIVA simply tells me what is the benefit of active management over the short and long term when looking at investing,” he says.
“The scorecard is really the data based, objective measure of active funds in Australia,” Lee says. “You can look at these historical performance data, but also consider the market conditions and what you have in your options, and then make a decision too.”the market conditions and what you have in your options, and then make a decision too.”
Laurence Parker-Brown is head of content at The Inside Network and managing editor of The Inside Adviser and Investor Strategy News.