Thursday 15th October 2026
Reporting season favoured delivery over promise
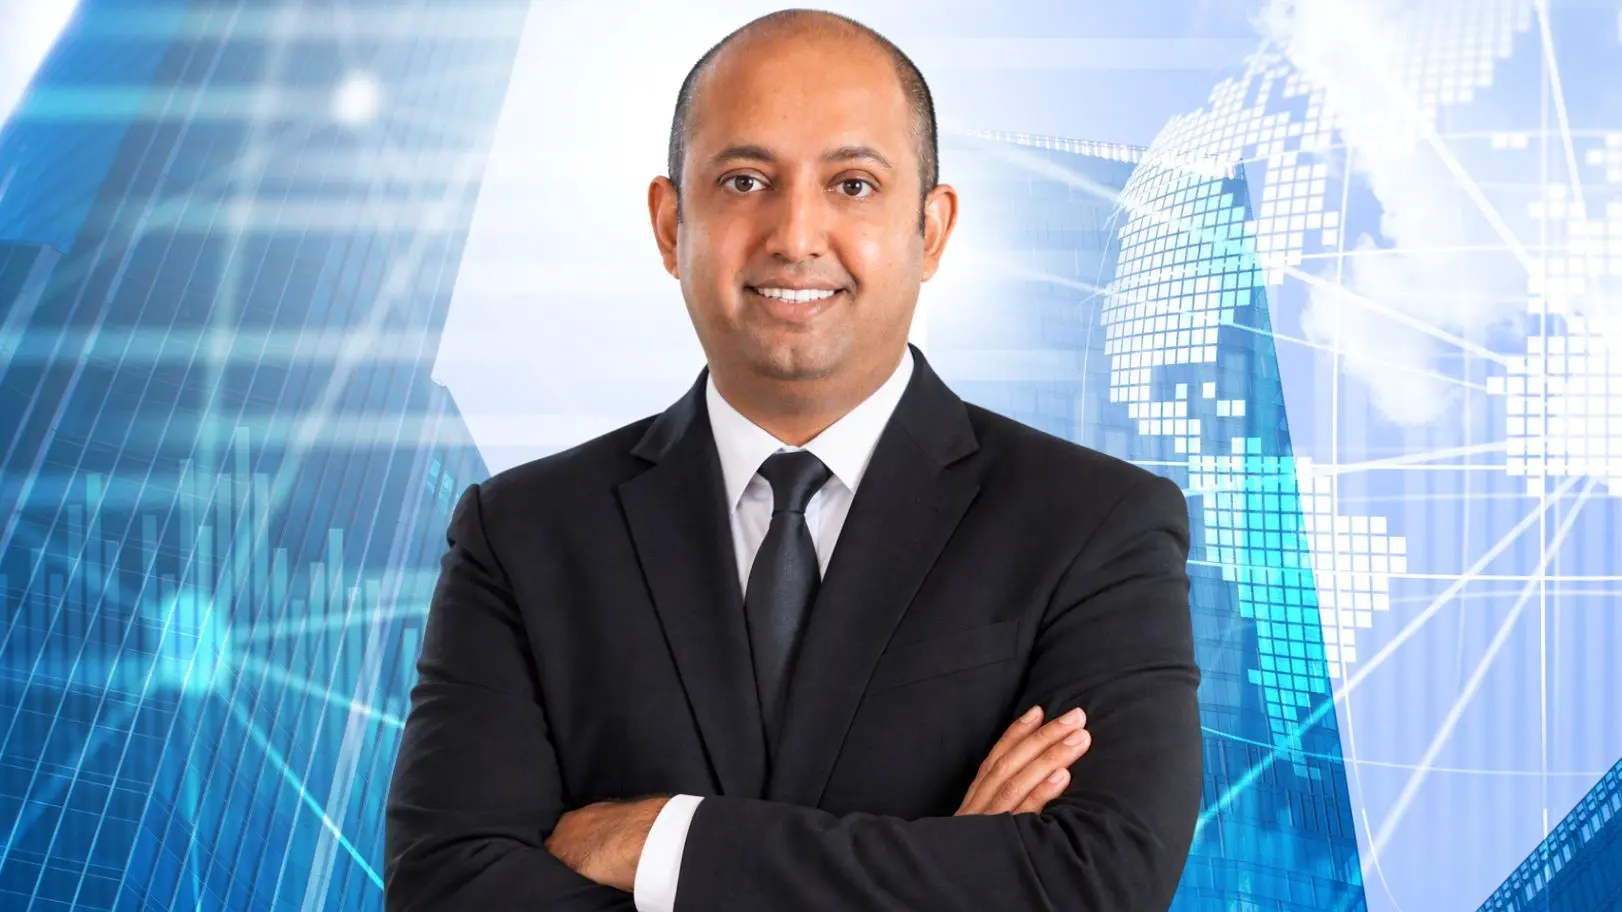
Datt Capital's Emanuel Datt says reporting season split the market into companies funding their own growth and those still asking shareholders to fund an ambition. His reads on lithium, gold and retail follow the same logic.
Australian company earnings came through the August reporting season broadly sound, which on most readings should have made for a quiet few weeks on the ASX. Investors punished anything short of outperformance.
Emanuel Datt, chief investment officer at Datt Capital, says the market spent the season separating companies that generate their own cash from those still asking shareholders to fund an ambition.
“I think the market is definitely at the point where it’s rewarding certainty over aspiration, and each sector has had its winners and losers, of course,” Datt says.
Certainty over aspiration
The companies that held their ground shared a short list of habits. They funded their own growth, held pricing power, allocated capital with discipline, grew cash flow, kept costs under control, and put new technology to work inside the business rather than in the investor presentation.
Datt describes the outcome as dispersion, the widening space between management teams doing those things and management teams content to hold the line.
Bravura Solutions stands out on his reading of the season. The software and services provider has beaten expectations consistently, and Datt credits an aligned shareholder base as part of the reason. He notes Datt Capital held no position going into the result, which makes the assessment a read on the company rather than a defence of a holding.
Technology more broadly is where he sees companies adopting AI to hold costs down rather than to win a headline, and he rates Bravura’s execution as exceptional.
That pattern gives advisers a cleaner test than the earnings numbers alone. A company that pays for its own growth can keep spending through a soft patch. A company that needs the market’s goodwill to fund the next stage of the plan discovers in August how conditional that goodwill has become.
The retail read
Online retail told the opposite story, with Datt watching Temple & Webster and Kogan for some firming in the fundamentals, finding little, and staying out of both ahead of their results. The broader sector looks weak to him, and the outlook offers little comfort.
The more instructive behaviour came from investors holding the retailers that did report well. Rather than adding to positions on a good result, they used the strength to take money off the table.
“You notice a big spike on the reporting day, then over time it slowly sells back down to where it was.”
Taxflation runs underneath that pattern, with tax changes aimed at individuals layering on inflation that has not gone away, leaving households with less to spend.
Datt traces the effect through to the discretionary retailers, where a thinner wealth effect turns up first in average order values and then in guidance. Households tighten the belt long before the macro data confirms they have.
Supply risk in lithium
Commodity prices move on supply far more often than on demand, and Datt applies that logic to lithium. Past severe El Nino events have brought heavier rainfall to South America, and Chile’s northern brine operations depend on the sun to concentrate lithium out of solution, so a wet season carries straight through to tonnes that never reach the market.
“Brines need to be evaporated with the sun, so excessive moisture isn’t good for how much supply makes it to market,” Datt says.
The forecast has firmed considerably since he made that argument. NOAA’s October 2026 update puts an 83 per cent probability on the three-month relative oceanic Nino index reaching at least 2.5 degrees for October to December, a level that would exceed every El Nino in a record running back to 1950, with strong to very strong conditions expected to hold into early 2027.
Australian hard-rock production does not carry the same weather exposure, which is the source of his interest in the domestic producers.
Energy market disruption from the Middle East adds to the case in his view, pushing more consumers towards electric vehicles and more industry towards battery storage, both of which draw on the same underlying commodity.
The variable worth watching from here is the supply response. The last lithium down cycle came from new tonnes rather than absent demand, with African spodumene and Chinese lepidolite arriving faster than the market could absorb, and Australian producers have shown they will bring idled capacity back when prices support it.
Weather can take supply out for a quarter or two, and how quickly restarts answer that is what decides how long the window stays open.
Energy and gold
Energy keeps its place in Datt’s thinking heading into the northern hemisphere winter, the traditional peak demand season and the period when supply interruptions carry the most weight.
That call has been tested since he made it and held up, with Houthi strikes on Saudi infrastructure taking Brent towards $100 in early September, Saudi Arabia closing the East-West pipeline on 13 September, and US crude passing $105.
Gold earns its place for different reasons, with global monetary settings on one side and sovereign buying on the other. China has bought a considerable amount of gold, well above its previous rate, and Datt reads that as a shift in the demand curve rather than a trade.
The results themselves fade quickly, and the habit the market rewarded in August will not. Companies funding growth out of the business rather than out of the next raising give advisers something they can hold through the second half of FY27, whatever the tape does between now and then.
Cristina is a contributor and content manager at The Inside Network.