

Monday 26th October 2026
Longer retirements are forcing a rethink of how drawdown portfolios get built
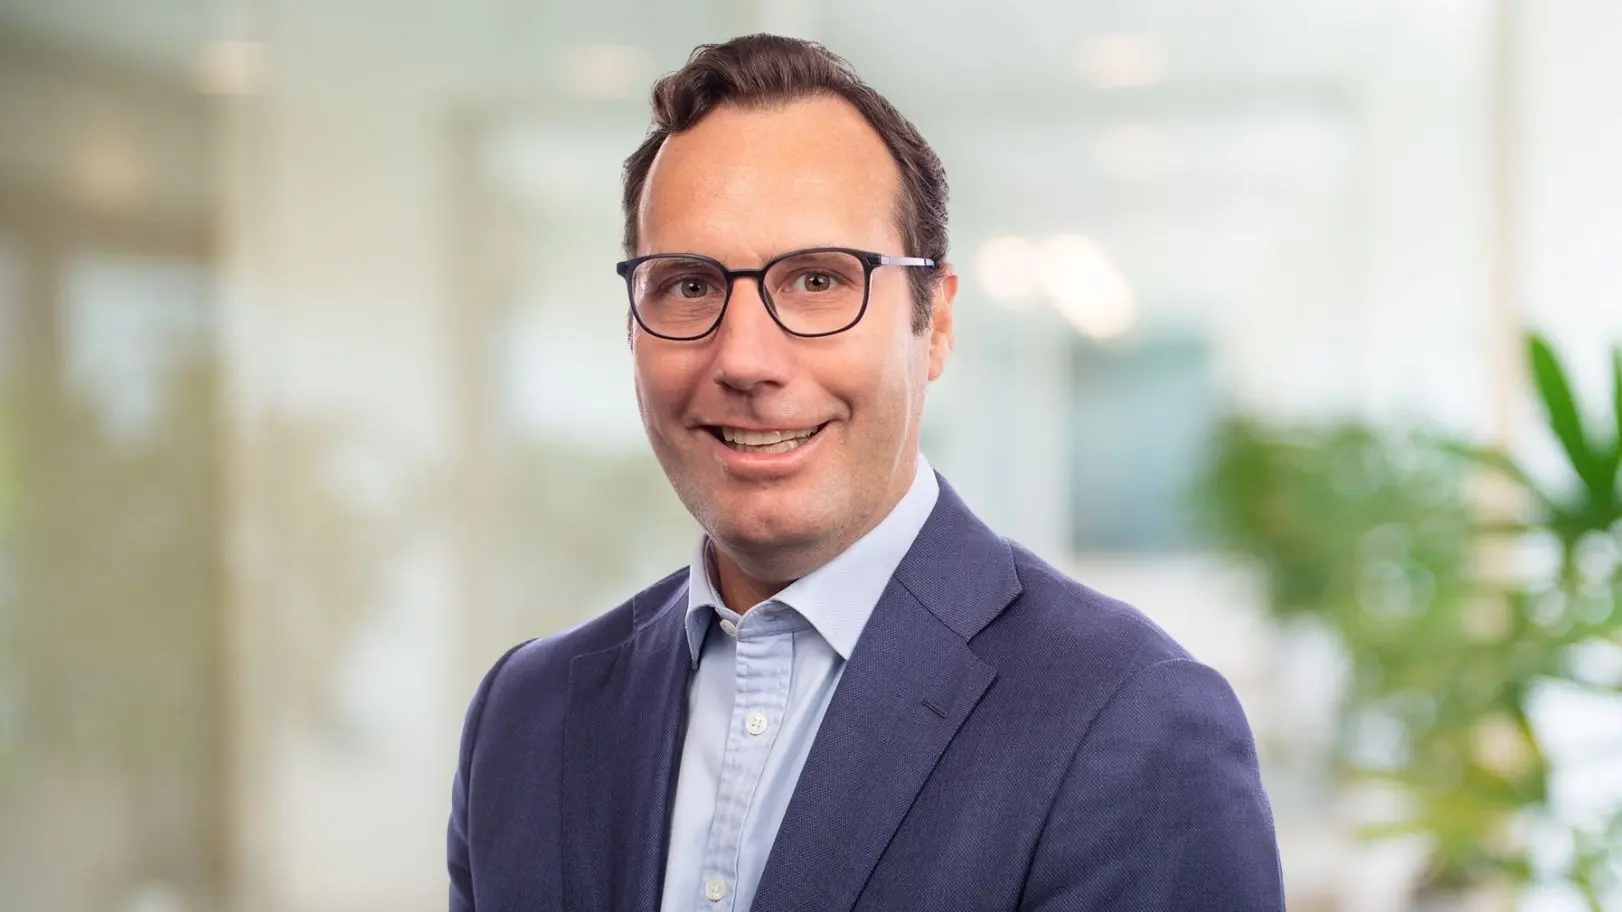
Russell Investments' Neil Rogan outlines a retirement income strategy that splits client assets across three time horizons, addressing sequencing risk and helping advisers fund drawdowns without selling growth assets into a falling market.
A client approaching retirement needs two things from the same pool of money. They need growth that has to last another two decades, and they need cash to live on from the moment they stop working. A single blended allocation struggles to deliver both at once.
The standard move has been to shift the client down the risk scale, take the volatility out of the portfolio and manage the drawdown from a more conservative position.
Neil Rogan, head of distribution, Australia and New Zealand at Russell Investments, argues that answer no longer fits the length of the job.
An estimated 2.5 million Australians will retire in the decade to 2035, on APRA and ASIC’s 2025 Retirement Pulse Check. Treasury’s 2023 Intergenerational Report puts the other half of the problem in view. People reaching 65 can expect to live for more than 20 additional years on average. A portfolio built to protect capital for five years has to fund four times that.
“Pre- and post-retirement is not a single investment phase,” Rogan says. “Clients still need long-term growth, but they are also drawing from their portfolio to fund their everyday living expenses.”
Building a retirement income strategy across three horizons
Russell Investments’ Retirement Solution is built around that tension, splitting client assets across three time horizons.
Near-term spending and liquidity go into a new Short-Term Portfolio, which focuses on income and capital stability. Future income needs go into a Medium-Term Portfolio, invested across income and moderate growth assets. Longer-term capital stays where it is, in whatever growth portfolio the client already holds.
A purpose-built Retirement Calculator sets the allocations across the three horizons and models a personalised glide path. It also guides rebalancing as spending patterns and balances change.
The investment logic underneath the structure is sequencing risk. It deserves more attention than it usually gets in client conversations.
Two retirees can earn an identical average return over 20 years. They can still finish with very different balances, purely because of the order in which those returns arrived.
The one who met a sharp drawdown in year two was drawing an income at the time. They sold units at depressed prices and had fewer of them left to recover with.
Separating assets by time horizon is designed to break that chain, because the withdrawals come from the short-term assets rather than from growth holdings that happen to be underwater.
“The challenge for advisers is balancing the money clients need to live on today with the assets that need to remain invested for the years ahead.”
What the behaviour is worth
Structure also does behavioural work, and Russell Investments’ 2026 Value of an Adviser research puts a number on that. The firm’s modelling of investors who regularly adjusted their exposure to the S&P 500 over the ten years to December 2025 found they gave up roughly 2.8 per cent a year against staying invested.
The Australian version of the same lesson is starker. A $100,000 investment in the S&P/ASX 300 over the ten years to December 2025 grew to $243,775 if the investor held through every session. Miss the ten strongest days and the same investment finished at $130,814. Miss 40 of them and the cumulative return turns negative.
A client who knows the next three years of income already rests outside the growth allocation has one fewer reason to make that call in the first place. The research also shows how little credit advisers get for it.
Behavioural coaching ranked first among the benefits advisers believe they provide, with 78 per cent strongly agreeing they add value by helping clients avoid costly mistakes during volatility. Clients ranked it last, on 27 per cent.
Good coaching leaves no trace, because the mistake never happened, and no client statement ever records the sale that was talked out of.
“Advisers shouldn’t have to rebuild a client’s portfolio just because a client is approaching retirement,” Rogan says.
The same research was conducted with almost 1,000 Australians in April and May 2026. It found reassurance about financial security has overtaken retirement planning as the main reason advised clients seek advice, on 43 per cent against 38 per cent.
Advisers have read that shift. Fewer now name retirement planning as a primary driver of advice, down from 90 per cent to 73 per cent on the previous year’s research, while guidance around financial choices rose from 28 per cent to 40 per cent.
Where the approach runs into limits
Time-segmented portfolios have their critics, and the objection is a fair one. Holding two or three years of spending in short-term assets carries a cost, and through a long bull market that cost compounds quietly against the client.
Javier Estrada, professor of finance at IESE Business School, tested three bucket strategies against 11 static allocations using 115 years of returns across 21 countries, running a 4 per cent initial withdrawal over 30-year retirements.
Static allocations generally left retirees better off. On the US data, the best static mix failed in no more than 1.2 per cent of those 30-year periods, while the best bucket strategy failed in 4.7 per cent of them.
Estrada’s conclusion was that the approach earns its place as a behavioural device rather than a financial one. That still counts, given what the missed-days numbers do to a balance, though advisers should be clear with clients about which of the two they are buying.
Both portfolios are available on CFS Edge, with a minimum investment of $5,000. Advisers can use them individually or together, and retain existing investments for the growth horizon.
Demand for this kind of thinking is running well ahead of supply. Padua WealthData put the register at about 15,170 in October 2026, barely half the number at the 2018 peak. Meanwhile, 2.5 million people move into drawdown by 2035.
Retirement income has become the problem the profession will be measured on. The advisers who can explain the retirement income strategy behind a client’s income, rather than only the return on it, will be the ones clients stay with through the first bad year.
Cristina is a contributor and content manager at The Inside Network.