Monday 2nd November 2026
Bonds are back but this no time to buy the index
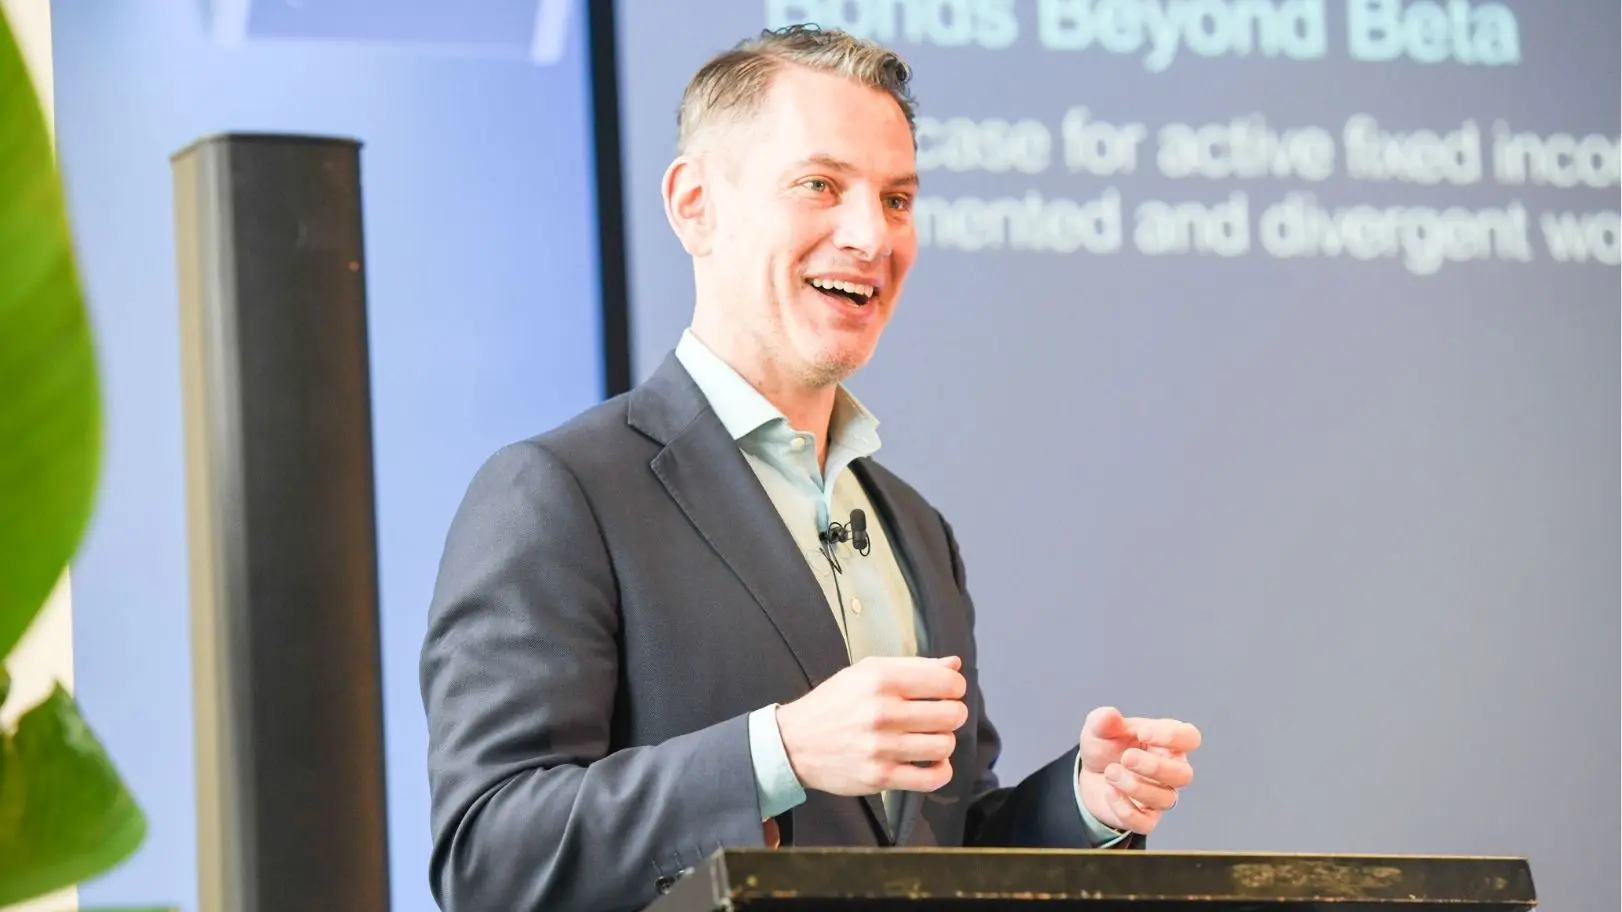
Franklin Templeton Fixed Income’s Richard Rauch says real yields have made fixed income worth owning again, and that advisers who get there through the global aggregate are buying a duration profile set by bond issuers rather than one their clients need.
Real yields are positive across most of the government bond universe for the first time in years. About two and a half per cent on a 10-year US inflation-protected bond, closer to 3 per cent further out the curve.
Against a client objective of CPI plus three to 4 per cent, that does much of the work on its own. Fixed income being worth owning again, though, is not the same thing as the fixed income index being worth owning.
Richard Rauch, senior client portfolio manager at Franklin Templeton Fixed Income, is blunt about the decade behind us. “Bonds could not even beat cash for the last 10 years. That is a pretty damning indictment.”
On his numbers, global bonds, the global aggregate and global sovereigns all trailed cash and Australian bank bills over the decade. High yield was the exception, with less duration risk and more yield, though spreads are now very tight.
Beta outcomes
The Bloomberg Global Aggregate is the default exposure for most portfolios and is increasingly treated as gospel. It holds predominantly sovereign investment grade debt, about six and a quarter year of duration, a sub 4 per cent yield, roughly 18 per cent corporate bonds and about 13 per cent mortgages.
The duration number deserves a second look. It sat around four in 1990, climbed to 7.5 by the lockdowns and is back near six and a quarter now, moving with the maturities that governments and companies choose to issue at. “There is no rhyme or reason for why the duration is what it is,” he says.
Whether that is the right duration for a client is a separate question from whether it is the index’s, and the index is not asking it.
Yields
The return on a bond portfolio, at least, is no mystery.
“If you tell me your yield, I can tell you what to expect. What you see is generally what you get.”
Treasury returns lagged by 10 years bear that out, the prospective 10-year return looks much like the current 10-year yield.
Two other things have turned. Bonds are beating cash again on a rolling three-year basis, and the curve is no longer inverted, so term premium and roll-down are available further out. Carry also gives a cushion that did not exist in 2021, a 100 or 200 basis point rise eats some or all of a year’s yield, but there is something to absorb it.
Dispersion and alpha
Rauch’s case for doing better than the index rests on divergence. Geopolitical risk and energy security are pulling fiscal and monetary policy apart, and government bond returns with them.
The Philippines imports all of its energy and is dealing with brownouts, an energy security problem and therefore an inflation problem. Latin America is the other side of that ledger, with high real yields and low or falling inflation in Mexico, Brazil and Colombia.
“I would rather be buying Brazil than India, given where the valuations are,” he says.
Currency risk is the price of admission to most of it. Fixed income is also not one asset, leveraged loans pay more as rates rise, interest-only structured products barely move with government bond markets, and the high yield index now carries relatively little duration.
The anchor problem
Rauch notes that bond and equity correlations are not stable and that the low or negative relationship advisers assume is not the norm. They spiked towards one after 2022 and again through the energy shock, and where inflation drives both, they move together. His qualification is that bonds will probably do all right in a crisis, without a guarantee.
That is the difficulty with the prescription. Trading interest rate risk for credit and currency risk moves a portfolio towards the exposures that fall alongside equities in a drawdown, which is when the anchor is supposed to hold. High yield and emerging market local currency debt did not diversify anyone in 2008 or in March 2020.
The same caution applies to his equity comparison. Rauch notes that history holds no instance of the Shiller PE at current levels followed by positive 10-year equity returns and offers short-dated high yield as a way to take chips off the table. He allows it might be different this time. The measure has also read expensive for most of the past decade, through a period when US equities returned a great deal.
Starting yields are the best they have been in 10 years, helping make the case that bonds are definitely back. The question for advisers is not whether to hold fixed income, It is whose duration they are holding, and why.
Laurence Parker-Brown is head of content at The Inside Network and managing editor of The Inside Adviser and Investor Strategy News.