Monday 21st September 2026
While others step back, Integro and Coastline build for risk
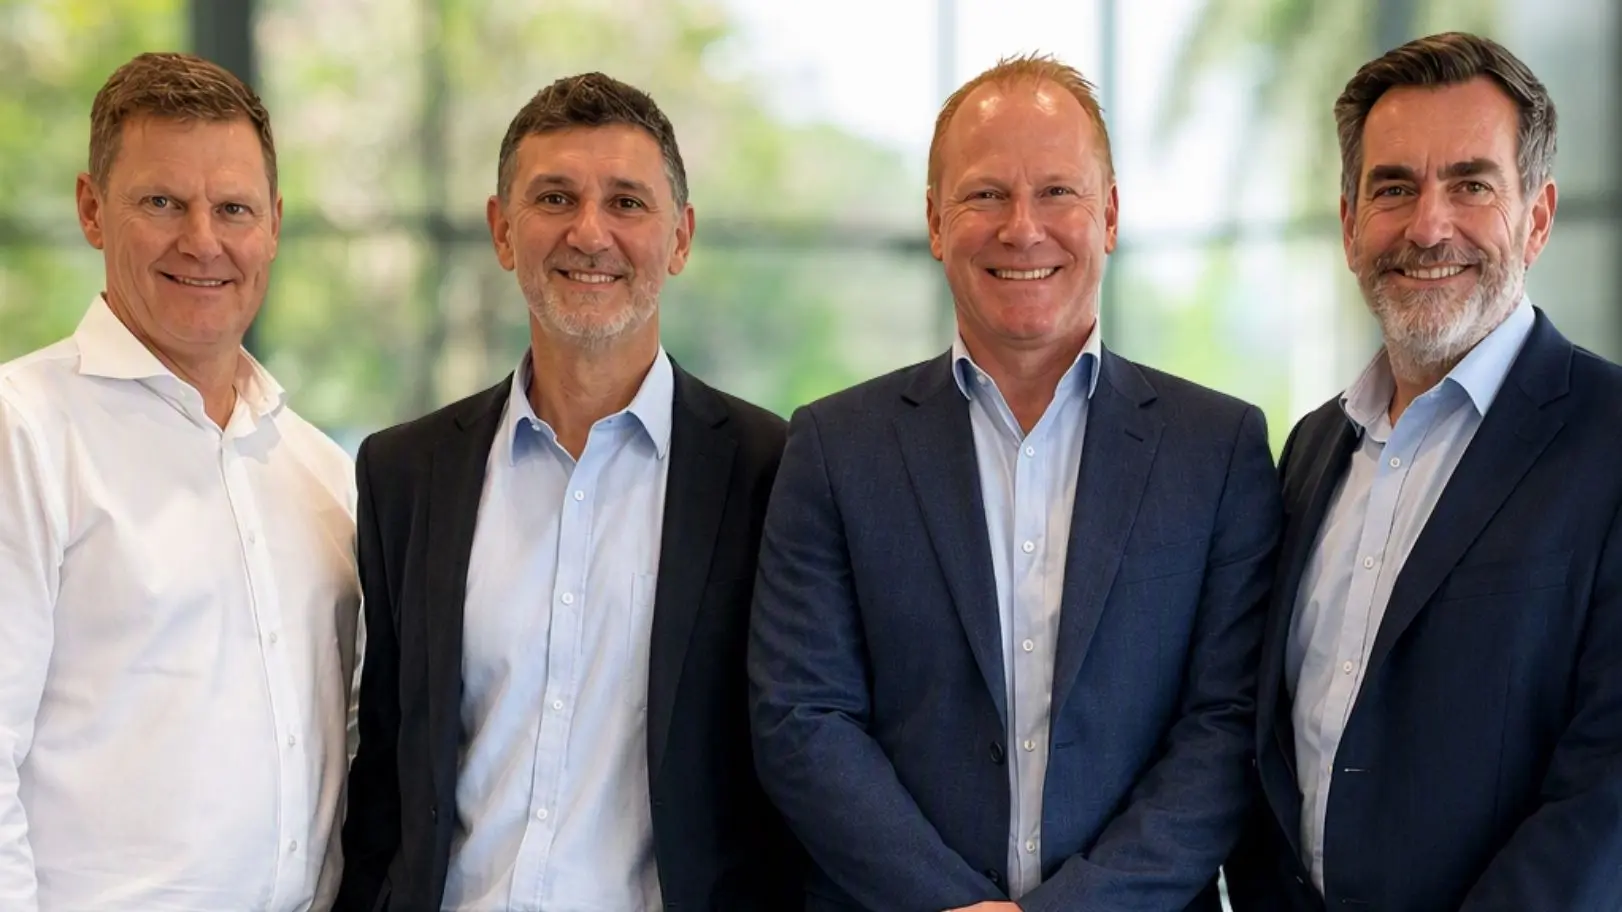
Most practices kept their risk advice licence and quietly stopped using it. Integro Private Wealth is moving the other way, merging with Coastline Private Wealth to build a specialist risk division as others retreat.
The Australian advice profession has spent six years shedding practitioners, and risk advice absorbed the heaviest of those losses.
Adviser numbers fell from roughly 28,000 in 2019 to about 15,600 by 2025, and the specialists who write life insurance for a living thinned out faster than the profession around them.
Adviser Ratings counted 185 “pure risk” writers and another 404 high-volume risk writers in 2024. Between them, that small group placed at least half of all new risk business in the country.
Against that backdrop, a Western Australian firm announcing it will build a dedicated risk division reads as a deliberate bet against the crowd rather than routine expansion.
Integro Private Wealth has merged with fellow WA advice firm Coastline Private Wealth and will stand up a specialist risk division inside its wealth management offering.
Coastline directors Alastair Fink and Joel Sharp join Integro with their team, and the group moves into Integro’s offices from 1 November 2026.
Integro, founded in 2003 and owned by its founders and staff, says it employs 30 people and advises individuals, family offices, native title trusts, not-for-profits and accounting partnerships.
Justin Gilmour, managing partner at Integro Private Wealth, was direct about the rationale.
“While many firms are stepping back from risk advice, we see a real opportunity to invest in and expand this capability.”
Why so many practices walked away
Advisers did not abandon risk business out of indifference. They walked because the numbers stopped working.
The Life Insurance Framework reset the economics in stages, and the ASIC instrument behind it capped upfront commissions at 60 per cent of the first year’s premium and ongoing commissions at 20 per cent from 1 January 2020.
The compliance burden attached to a single income protection recommendation stayed exactly where it was. Underwriting a client, documenting the advice, arranging medicals and shepherding an application through to acceptance can absorb weeks of practice time. Charging a fee that covers that work tends to lose the client.
The claims side adds another layer of difficulty. When a client is diagnosed, disabled or bereaved, the adviser who wrote the policy fields the call. That work rarely appears in a revenue line and does not scale the way an investment book does. A risk book carries those obligations for years, and the practice absorbs them regardless.
That pattern shows up clearly in the data with 83 per cent of advisers holding registration to give life insurance advice. Yet only 6 per cent focus on it. Most practices keep the licence and quietly stop using it.
What a specialist division changes
Integro’s central argument is that separation changes the economics. Once risk advice runs as its own division with its own people, the specialists write enough volume to justify the process investment, and the wealth advisers stop treating insurance as the least attractive job on the desk.
Gilmour said the merger brings capability Integro wants to spread across its whole client base.
“Coastline Private Wealth has always been strong in this area, and the merger will mean their industry leading expertise is available to all Integro clients,” he said.
For advisers watching from other practices, the more interesting part is the model rather than the deal. A dedicated risk function concentrates the skills that decay fastest when they go unused: reading underwriting terms, structuring ownership so a payout lands in the right hands and does not trigger tax, sequencing cover alongside SMSF and business succession arrangements, and running a claim to conclusion.
Practices without that capability increasingly buy it through referral relationships, which brings its own questions about who holds the client relationship and who wears the advice risk.
The economics have improved, but only just
Integro is moving into a market that has begun to recover rather than one that has healed. New business volumes reached $331 million across the 2024-25 financial year, a four-year high, and still 42 per cent below the $568 million written before the Hayne royal commission.
Growth from a low base is progress, though it is not a return to the old market. Premium pricing is the live threat the division inherits.
APRA and ASIC opened joint work in 2022 into increases the regulators described as “repeated, large and unexpected”, and further findings are due later this year.
Every one of those increases tests a client’s willingness to keep paying, and lapse rates punish the adviser who wrote the cover rather than the insurer who repriced it.
A specialist division inherits that exposure at scale. Coastline’s book will earn its keep only if the combined business can hold clients through the next repricing cycle, and scale alone has never solved that problem.
Continuity is the harder half of any merger
Fink described the deal as an extension of what Coastline already built.
“Joining forces gives us the opportunity to retain the things that have made Coastline successful, while providing our clients and team with access to greater resources, expertise and opportunities,” he said.
Sharp made a similar point about the team, saying the merger opens “more opportunities to collaborate, develop and broaden what we can offer clients”.
Advice mergers rarely fail on strategy. They fail when the acquired firm’s clients discover that the person who knew their circumstances has moved on, or when the incoming team finds its process replaced rather than adopted.
Both Coastline directors joining, along with their team, gives the arrangement a reasonable chance. Retention structures in advice mergers rarely hold when the key people leave first, and the co-location date of 1 November 2026 marks the start of that test rather than the end of it.
Where this leaves advisers
Consolidation among WA advice firms has been running for several years, and most of it has pointed the same way: bigger investment and retirement offerings, thinner insurance capability.
Integro has chosen the opposite direction, and the reason is worth attention regardless of whether the model works.
Australians remain badly underinsured, the number of people qualified and willing to fix that keeps falling, and the practices that retain the skill will hold something their competitors can no longer supply in-house.
Advisers who exited risk years ago face a simpler question now than they faced then. Who do they trust to write the cover their clients still need?
Cristina is a contributor and content manager at The Inside Network.